Distribution: net assets, liquidity and report
The net asset test and the liquidity test before every distribution, and the board’s report that documents them.
Updated on
What the module delivers
Before a dividend, directors’ profit shares or a repayment of contribution, Fiplan calculates the net asset test and the liquidity test, on the company’s position and on the months after the payment, then drafts the board’s report (art. 5:142 and 5:143 BCCA for a private limited company).
The five steps
- Position — on which accounts?
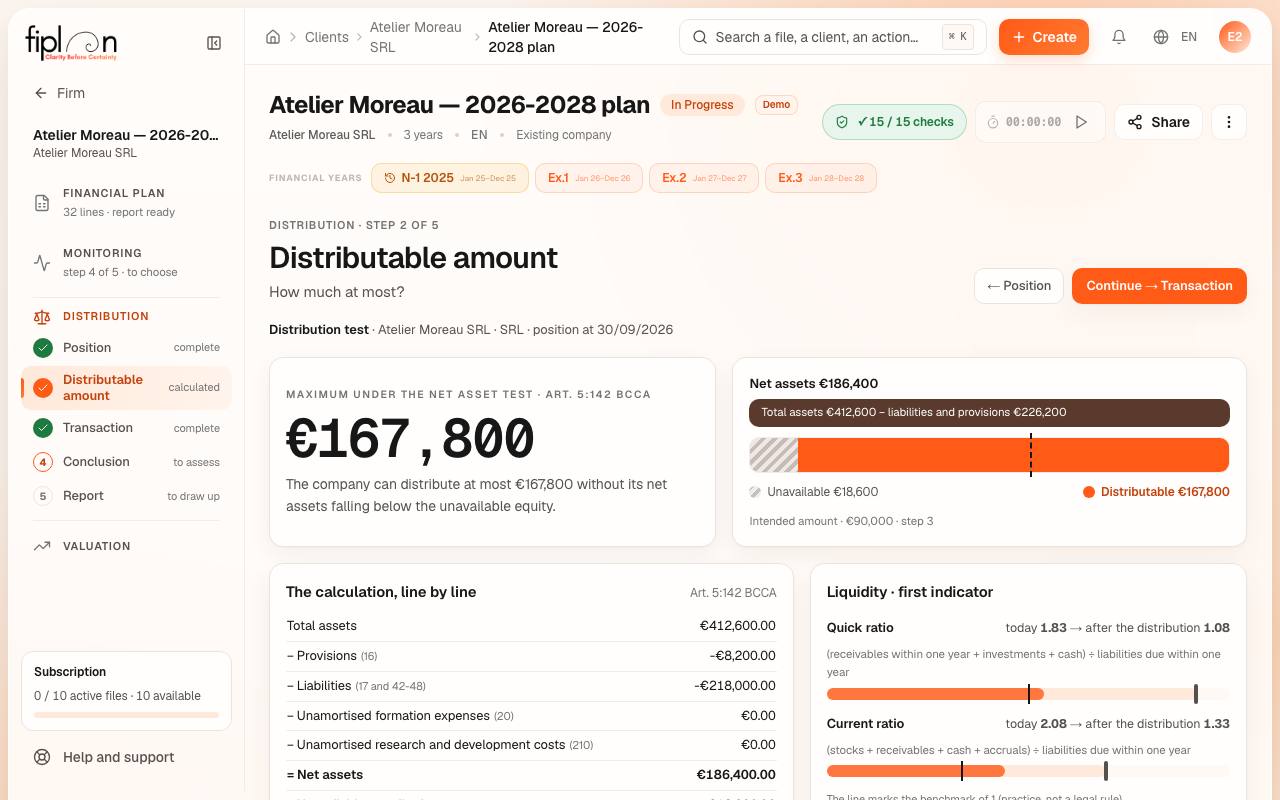
- Distributable amount — how much at most?
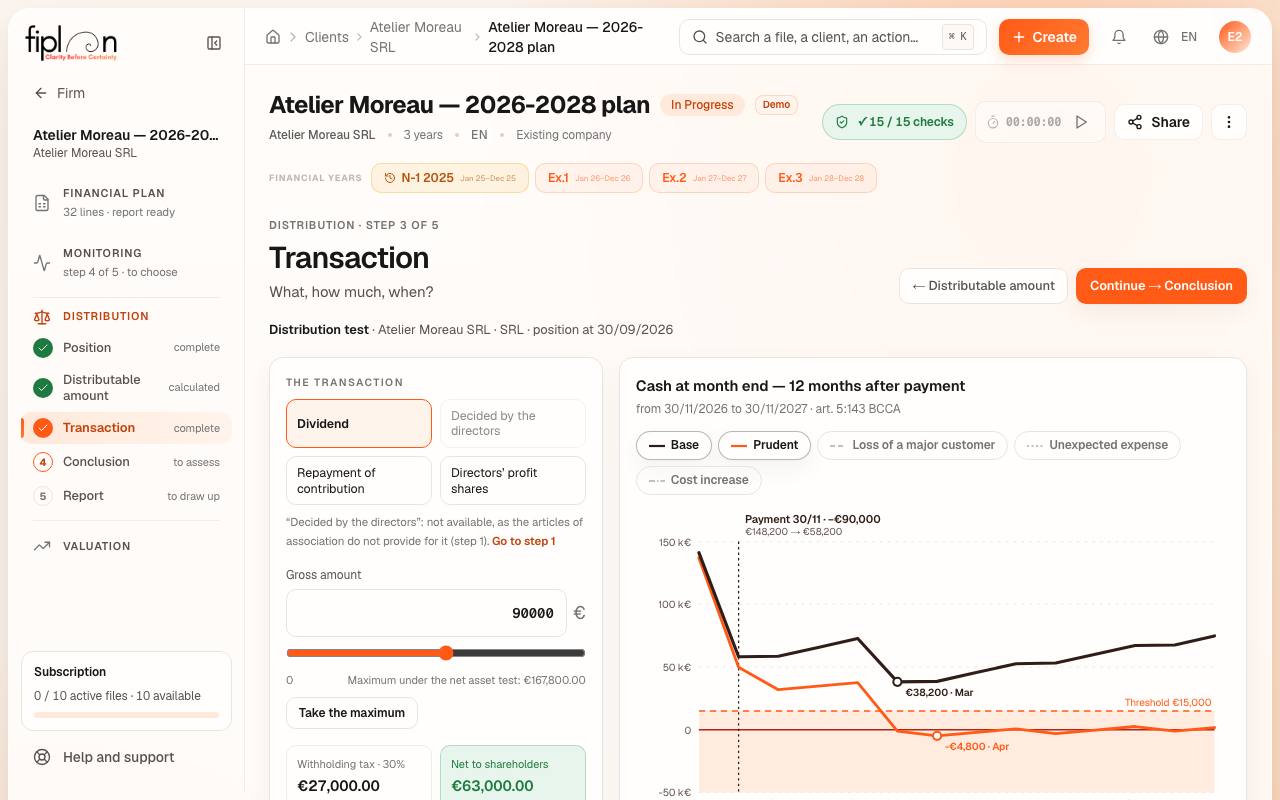
- Transaction — what, how much, when?
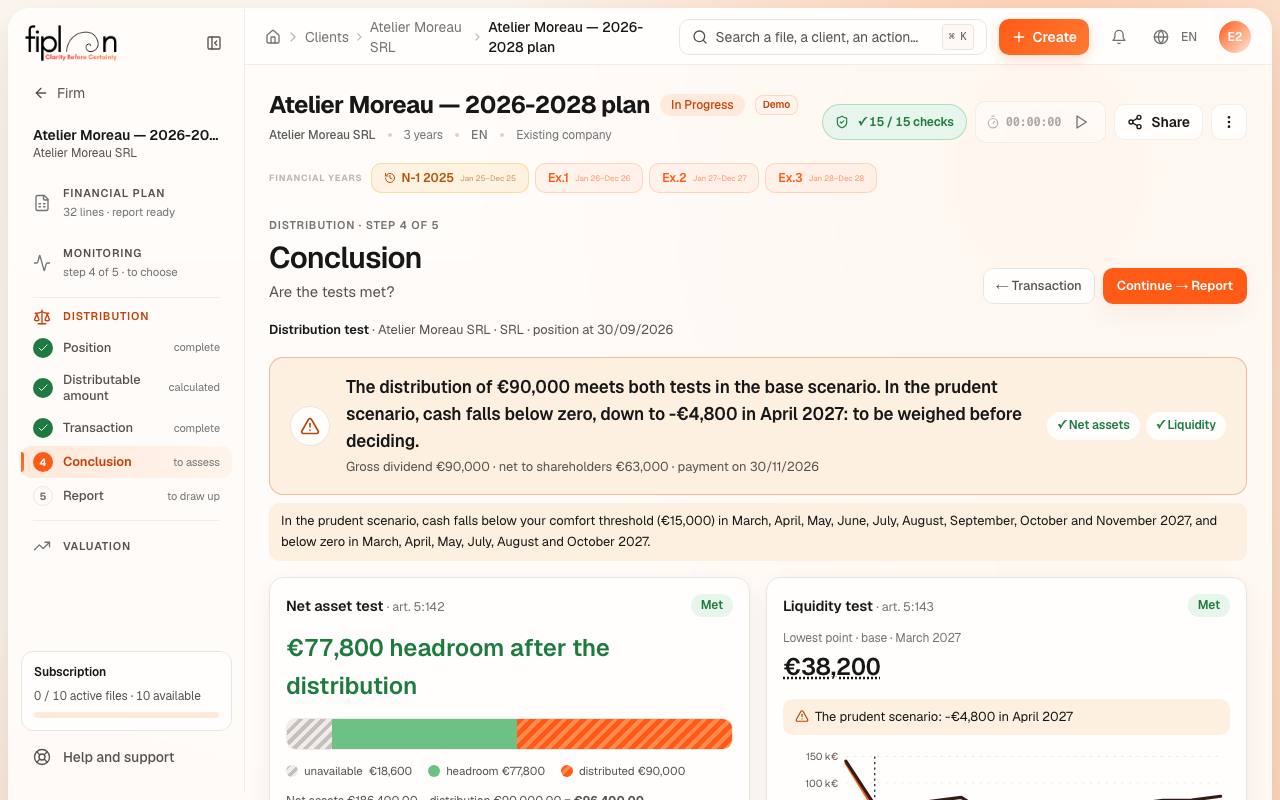
- Conclusion — are the tests met?
- Report — what is handed over?
What the module produces
- The board’s report, in PDF and in Excel.
- Its annexes: the monthly cash flow, the proposed entries and the statement before payment.
- The documents in French, Dutch and English.
What sets it apart
- Adverse scenarios: prudent, loss of a major client, unexpected expense, rising costs.
- “How much can be distributed at most?”: the amount the two tests allow.
- “Is it reasonable?”: meeting the tests is not always enough; the answer remains your judgement.
- The established, dated version: “Establish the version” freezes the figures and your answers, with its author.
- The plan’s journal on the PCMN behind the position and the cash flow.
On screen
Frequently asked questions
Which company forms?
The private limited company (art. 5:142 and 5:143 BCCA), the cooperative company (art. 6:115 and 6:116 BCCA) and the public limited company (art. 7:212 BCCA).
What does the report contain?
The position, the two tests, the planned transaction and, in annexes, the monthly cash flow, the proposed entries and the statement before payment.
Does the client see the distribution report?
No: it stays with the firm. You hand it over yourself, in PDF or in Excel.