
The distribution test
May a company distribute, and how much? The Distribution module starts from a position (a trial balance, the last approved accounts or the plan's figures), calculates net assets, projects cash month by month and drafts the report. It judges; it writes nothing to the journal.
What it is for
A distribution to the shareholders of a BV/SRL or a CV/SC must pass two tests: the net asset test (net assets must not fall below what the law or the articles of association make unavailable) and the liquidity test (the company must be able to pay its debts during the twelve months after the payment). An NV/SA only has the first. The file's Distribution module runs these tests on a recent position, says how much the company can distribute and prepares the distribution report that the board draws up before the payment. The module's screen is in French; the labels below are quoted as the screen shows them.
The module follows the modules' common bar: ① Data, ② Checks, ③ Assumptions, ④ Result, ⑤ Report. Each step is validated before the next; a step changed afterwards sets the following ones back to To review.
Steps
- Open the file, Distribution module, then “Commencer un test de distribution” (start a distribution test).
- ① “Sur quelle situation porte le test?” (which position does the test cover?) — choose the source: “Une balance récente” (a recent trial balance, imported in Monitoring or here), “Les derniers comptes approuvés” (the last approved accounts: the file's prior year, with the approval date) or “Les chiffres du plan” (the plan figures, at the end of the chosen month). Check the company's legal form (client record), the “Commissaire” (statutory auditor), and say whether “Les statuts permettent aux administrateurs de distribuer” (the articles allow the directors to distribute): with no answer the box stays unticked — nothing is guessed.
- ② “Combien la société peut-elle distribuer?” (how much can the company distribute?) — read the “Actif net” (net assets), the “Indisponible” (unavailable) and the “Maximum distribuable” (maximum distributable), the line-by-line calculation and its cross-check, then the ratios.
- ③ “L'opération” (the operation) — choose the operation: “Dividende” (dividend), “Décidée par les administrateurs” (decided by the directors), “Remboursement d'apport” (repayment of contributions) or “Tantièmes” (directors' profit shares); then the “Montant brut” (gross amount), the “Date de paiement” (payment date), the “Horizon” (at least 12 months) and how the projection is filled: “Projection rapide depuis la balance” (quick projection from the trial balance) or “Reprendre le plan du dossier” (take over the file's plan). Set, if you wish, a “Seuil de confort” (comfort threshold) and the scenarios.
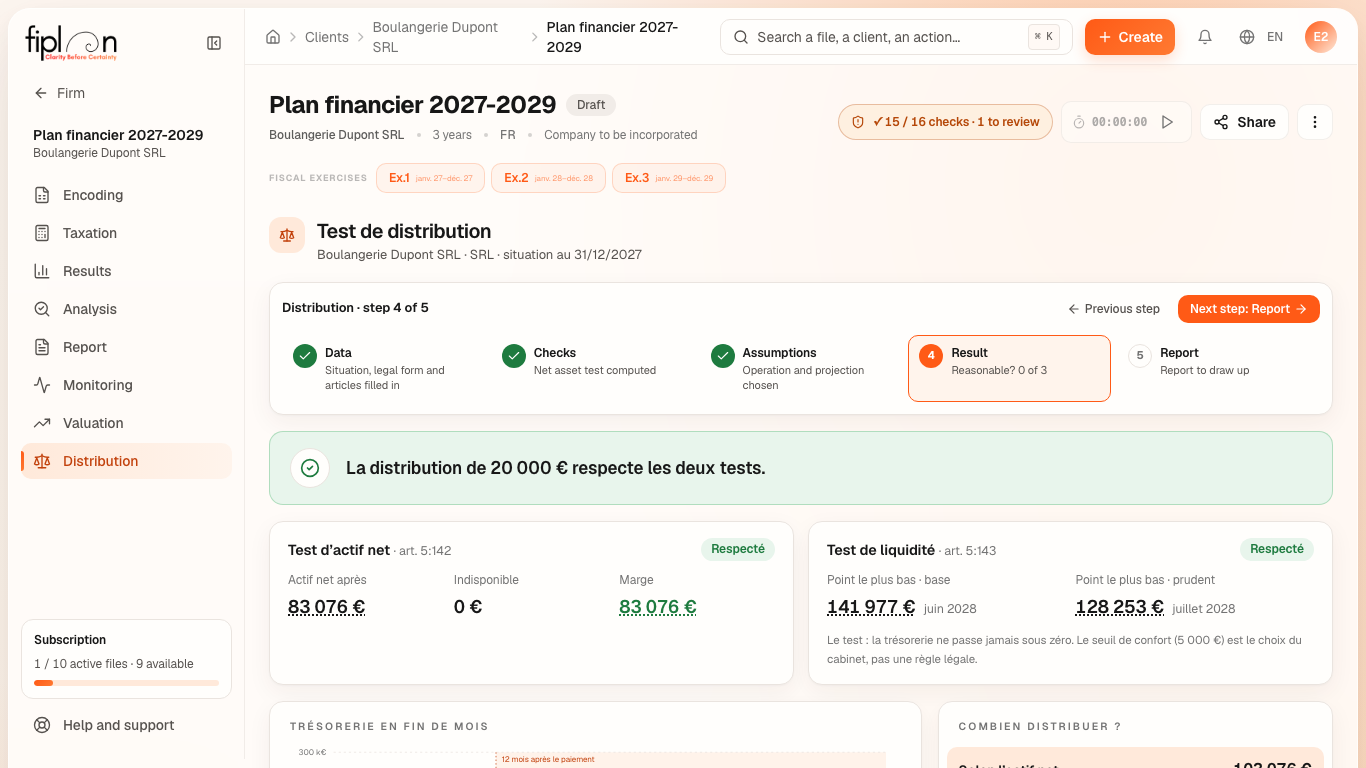
- ④ Result — read the verdict, the two tests, the “Trésorerie en fin de mois” (month-end cash) chart, “Combien distribuer?” (how much to distribute?), and answer the three questions of “Est-ce raisonnable?” (is it reasonable?).
- ⑤ Report — compose the report, download the PDF or the Excel, then “Établir le rapport” (draw up the report).
The firm's Distribution page (Work menu) lists the latest test of each file: the company and the operation, the amount and its payment date, the state of the two tests, the path and the report. New distribution test asks for the Company file, then Open the distribution.
Worked example · Boulangerie Dupont SRL
The bakery plans the gross dividend of €20,000.00 of its profit appropriation, paid on 30 June 2028. Before deciding it, the test is run on “Les chiffres du plan” (the plan figures) at the end of the 2027 financial year (31 December 2027), with the “Reprendre le plan du dossier” (take over the file's plan) projection over 12 months and a comfort threshold of €5,000.00.
| What the module returns | Amount |
|---|---|
| Net assets at 31 December 2027 | €103,076.13 |
| Unavailable (the bakery's contribution is available) | €0.00 |
| Maximum distributable | €103,076.13 |
| Net assets after the dividend | €83,076.13 |
| Lowest cash after the payment · base scenario | €141,976.88 |
| Lowest cash after the payment · prudent scenario | €128,253.00 |
| Withholding tax (30%) | €6,000.00 |
| Net to shareholders | €14,000.00 |
Both tests are met: the margin over unavailable equity remains €83,076.13, and cash never falls below zero from 30 June 2028 to 30 June 2029. The smallest possible amount is the net assets one, €103,076.13.
Pitfalls
What it changes · 2028
Source
Net asset test: art. 5:142 BCCA (BV/SRL), 6:115 (CV/SC), 7:212 (NV/SA); liquidity test: art. 5:143 (BV/SRL) and 6:116 (CV/SC), an NV/SA has none (src/lib/tests-distribution.ts; docs/references/affectation/SOURCES.md A7, A8, A10). NV/SA: CBN/CNC opinion 2021/02; BV/SRL: IBR/IRE technical note 2019/15. Withholding tax: standard rate from the rules file (computeWithholding, tax sources R21). Reasonableness: Cass., 23 May 2024, cited as a mention.