
Financial coherence checks
An entered line promises entries: a depreciation charge each year, a repayment each month, VAT on every sale. The “Financial Coherence” category checks that the plan contains them, and that the reduced rate of corporate income tax is secured.
What it is for
In the Plan checks panel, the Financial Coherence category groups:
- Depreciation coherence: the depreciation charges in the income statement equal the depreciation schedule of the investments; accumulated depreciation does not exceed the gross value.
- LT/ST debt vs schedules: a repayable financing does have a long-term debt on the balance sheet, and no debt is negative.
- VAT consistency: a standard VAT taxpayer (assujetti ordinaire / gewone btw-plichtige) that sells charges VAT; a file under the small business scheme (franchise / vrijstellingsregeling), exempt or not subject to VAT records none.
- SME reduced-rate eligibility: the conditions for the SME reduced rate of corporate income tax (impôt des sociétés / vennootschapsbelasting) are filled in for each financial year. This check is never in error; at most it is to review.
When a reduced-rate condition is not filled in, the check is to review and shows, below its title, always visible: the missing conditions, named one by one; a table Taxable base · CIT at the reduced rate · CIT at the standard rate · Difference, per financial year and for the Plan; the formula of the difference; and the sentence “This reservation also appears in the PDF report.”. When a condition is set to “Non”, the standard rate applies: the check stays OK, and its detail writes the reason for each financial year.
Steps
- Open the Plan checks panel from the checks badge.
- Read the Financial Coherence category.
- For reduced-rate eligibility, read what is at stake below the title, then click Complete in Taxation: the Taxation tab opens, where you answer the conditions.
- Expand a check (▾) to read its detail financial year by financial year.
Worked example · Boulangerie Dupont SRL
| Check | State |
|---|---|
| Depreciation coherence | OK |
| LT/ST debt vs schedules | OK |
| VAT consistency | OK |
| SME reduced-rate eligibility | Warning |
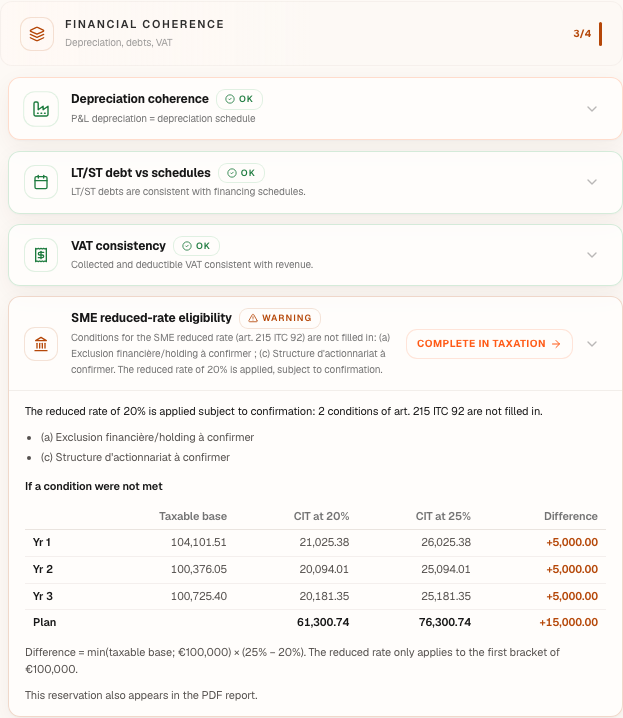
The bakery has not yet answered conditions (a) and (c) of the reduced rate. The check is to review and writes: “The reduced rate of 20 % is applied subject to confirmation: 2 conditions of art. 215 ITC 92 are not filled in.” Then, if a condition were not met:
| Financial year | Taxable base | CIT at 20% | CIT at 25% | Difference |
|---|---|---|---|---|
| 2027 | 104,101.51 | 21,025.38 | 26,025.38 | +5,000.00 |
| 2028 | 100,376.05 | 20,094.01 | 25,094.01 | +5,000.00 |
| 2029 | 100,725.40 | 20,181.35 | 25,181.35 | +5,000.00 |
| Plan | 61,300.74 | 76,300.74 | +15,000.00 |
The screen spells it out: “Difference = min(taxable base; €100,000) × (25 % − 20 %). The reduced rate only applies to the first bracket of €100,000.” This check gives the file's checks badge, orange: ✓ 15 / 16 checks · 1 to review (“EBITDA coherence”, not applicable, is not counted).
Pitfalls
What it changes · all financial years
Source
Art. 215 of the Income Tax Code 1992 (CIR 92 / WIB 92): the conditions for the reduced rate of corporate income tax, the 20% rate on the first bracket of €100,000 (see the Tax chapter; docs/references/fiscal/SOURCES.md, R1, R2).
Fiplan conventions (financial-controls.ts, reserve-taux-reduit.ts): the thresholds for the gaps (one cent, €100), the states of each check, and what is at stake for the reduced rate — the difference, to the cent, between CIT at the standard rate and CIT at the reduced rate — are those of the code.