
Input compliance
A line can be posted correctly in the journal and still break a rule: an asset depreciated on a declining-balance basis, a subsidy never released to profit, land being depreciated. The “Input compliance” category names these lines, one by one, and says what to do.
What it is for
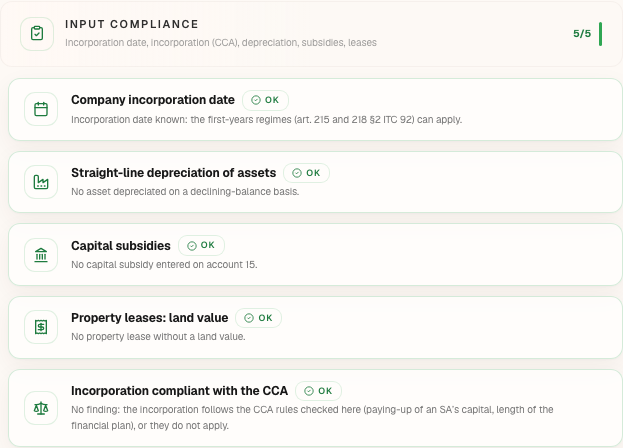
In the Plan checks panel, the Input compliance category groups five checks. Each one is OK without the case, and to review (Warning) with it, never in error: its text names the lines concerned, in quotation marks, and ends with “To do: …”.
| Check | To review when… | What to do |
|---|---|---|
| Company incorporation date | the client's record does not show the date of incorporation, for a file that is not an incorporation: the first-years regimes (art. 215 and 218, § 2 of the Income Tax Code 1992, CIR 92 / WIB 92) are not applied | enter it on the client's record — the check has no button |
| Straight-line depreciation of assets | an old investment line is still depreciated on a declining-balance basis | Fix opens the encoding, Investments module: switch it back to straight-line |
| Capital subsidies | an old line of Financing & Contributions carries a subsidy on account 15: it is never released to profit | Fix opens Financing & Contributions: enter the subsidy in the Subsidy amount field of the investment it finances, then delete the line |
| Property leases: land value | a property lease has no land value: the whole asset is depreciated, land included | Fix opens Financing & Contributions: fill in the Land value on the lease line |
| Incorporation compliant with the CCA | an incorporation created before this check does not follow the Companies and Associations Code (CSA / WVV): the paid-up capital of an SA, or a plan shorter than two years from incorporation | the paid-up part of the contribution (Fix, Financing & Contributions); the length of the plan, in the file settings, with no button |
Steps
- Open the Plan checks panel from the file's checks badge.
- Scroll down to the Input compliance category: its header counts the checks that are OK, out of five.
- Read the text of a check to review: it names each line concerned and ends with what to do.
- Click Fix when it is shown: the panel closes and the encoding opens on the right module.
- Correct the line and save: the check turns back to OK, and the badge with it.
Worked example · Boulangerie Dupont SRL
| Check | State |
|---|---|
| Company incorporation date | OK |
| Straight-line depreciation of assets | OK |
| Capital subsidies | OK |
| Property leases: land value | OK |
| Incorporation compliant with the CCA | OK |
The bakery was incorporated on 4 January 2027: the date is known. Its plan runs to the year-end of December 2029, beyond the 24 months that the Companies Code requires from incorporation. It has no declining-balance line, no subsidy on account 15 and no lease: all five checks are OK.
If the van were an old line still marked as declining-balance, the “Straight-line depreciation of assets” check would turn to Warning and write:
- Declining-balance depreciation on « Camionnette de livraison »: not allowed for a company for assets acquired from 01/01/2020 (art. 196, § 3 ITC 92). To do: switch these lines back to straight-line (Encoding › Investments).
The badge would count this extra check to review: “✓ 14 / 16 checks · 2 to review”.
Pitfalls
What it changes · all financial years
Source
Art. 215 and 218, § 2 of the Income Tax Code 1992 (ITC 92; CIR 92 / WIB 92): the first-years regimes, counted from incorporation (docs/references/fiscal/SOURCES.md, R6, R20). Art. 196, § 3 ITC 92: no declining-balance depreciation for a company, for assets acquired from 01/01/2020 (T12).
Royal Decree of 29/04/2019 implementing the Companies Code (AR CSA / KB WVV): art. 3:89, § 2, V — a capital subsidy is released in step with the depreciation of the asset it finances; art. 3:42 — land is not depreciated (texts reread in the MOTEUR-3 and MOTEUR-4 batches, docs/rapports/MOTEUR-3-detail.md, MOTEUR-4-detail.md).
Companies and Associations Code (CSA / WVV): art. 7:11 — the capital of an SA paid up at incorporation; art. 5:4, 6:5 and 7:3 — a financial plan of at least two years from incorporation (register, D263 and D271).
Fiplan convention (financial-controls.ts, reserves-fiscales.ts, constats-constitution.ts): one check per case, to review, never blocking; no existing line changed; Vaga's decision V-14 for account 15.