
Entering an investment
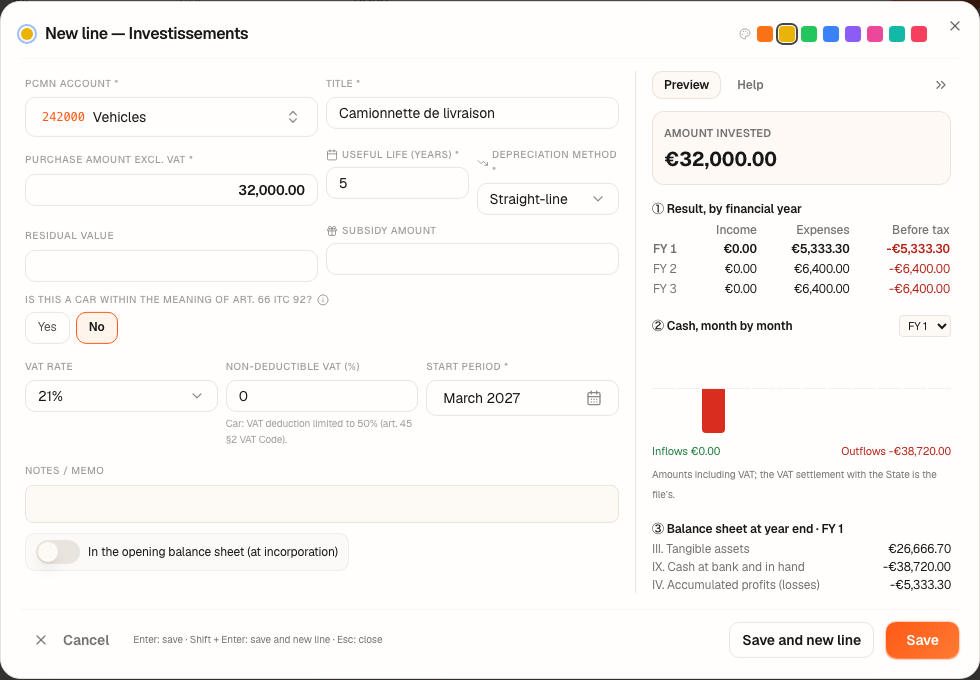
A delivery van does not cost €32,000 in the financial year it is bought: it wears out over five years. Fiplan records it as an asset and spreads its cost over its useful life — depreciation — in a line it creates itself.
What it is for
An investment (class 2) is an asset that the business uses for several years. Its purchase leaves cash in the month it is paid; its expense, the depreciation charge (dotation aux amortissements / afschrijvingen), is spread over its useful life.
Steps
- Open Encoding, then Investments, and click New.
- Choose the asset's PCMN Account, the account in the Belgian minimum chart of accounts (PCMN / MAR) — for example
242000, vehicles — and the Title. - Enter the Purchase amount excl. VAT.
- Enter the Useful life (years) (from 1 to 33). The Depreciation method is straight-line.
- If the asset will be sold at the end, its Residual value; if it is subsidised, the Subsidy amount.
- On a 240000 or 242000 account, answer Is this a car within the meaning of art. 66 ITC 92?: No if the asset is neither a car, nor a dual-purpose vehicle, nor a minibus; otherwise Yes, then enter the Deductible share (%) of this car's costs — Fiplan proposes none, and saving waits for it.
- Check the VAT rate (21% proposed) and, if the VAT is not fully deductible, the Non-deductible VAT (%).
- Choose the Start period: the month of purchase. Read the breakdown on the right and click Save. Fiplan creates the line “Depreciation – …”.
Worked example · Boulangerie Dupont SRL
A delivery van at €32,000.00 excl. VAT, VAT 21%, bought in March 2027, depreciated over 5 years, with no residual value.
| Breakdown | Amount |
|---|---|
| Price excl. VAT | 32,000.00 |
| VAT | 6,720.00 |
| of which recoverable | 6,720.00 |
| Depreciable cost | 32,000.00 |
Annual depreciation charge (account 630200) | 6,400.00 |
Each annual instalment is spread over the twelve months following the purchase, i.e. €533.33 per month (the remaining cent falls in the twelfth month). Financial year 2027 carries 10 months (March to December).
| Financial year | Depreciation charge | Net book value at 31 December |
|---|---|---|
| 2027 | 5,333.30 | 26,666.70 |
| 2028 | 6,400.00 | 20,266.70 |
| 2029 | 6,400.00 | 13,866.70 |
On account 242000, the window asks the art. 66 question. The running example answers No — an assumption of the example: the van is neither a car, nor a dual-purpose vehicle, nor a minibus. If it were a car with a deductible share of 75%, Fiplan would add back 25% of each depreciation charge as a disallowed expense: €1,333.33 in 2027, on the financial year's €5,333.30 depreciation charge.
Pitfalls
What it changes · 2027
Source
Minimum standard chart of accounts (plan comptable minimum normalisé / minimumindeling van een algemeen rekeningenstelsel, annex 1 to the Royal Decree of 21 October 2018): class 2 (24: furniture and vehicles; 249: accumulated depreciation) and account 630 (depreciation charges).
Income Tax Code 1992 (CIR 92), Article 196, § 3: declining-balance depreciation excluded for companies; Article 66 (amended by the Law of 25 November 2021): the deductible share of the costs of a car, a dual-purpose vehicle or a minibus (FPS Finance, notes to the corporate income tax return, tax year 2026, p. 18-19). The non-deductible share of depreciation is added back as a disallowed expense (voiture-dna.ts).
Fiplan conventions, declared in the code (plan-amortissement.ts, companion-depreciation.ts): annual instalments split to the cent with nothing lost; each instalment runs over twelve months from the month of purchase.