
Capital subsidies
An investment grant is not taken to income on the day it arrives: it goes with the asset it finances, and is released to income as that asset is depreciated.
What it is for
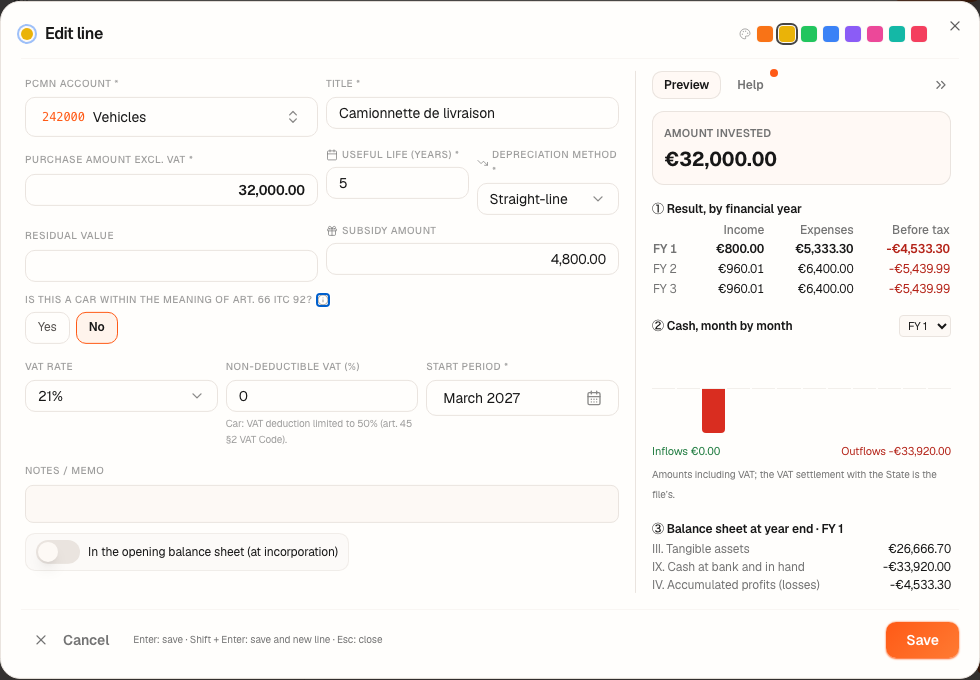
The subsidy is a field of the investment line: the Subsidy amount. Fiplan records it on account 150000 (capital subsidies, subsides en capital / kapitaalsubsidies, in equity) in the month of acquisition, then each month releases a share of it to income, on account 753000, in proportion to the asset's depreciation charge (dotation aux amortissements / afschrijvingen).
Steps
- Open Encoding, then Investments, and open the asset's line (or create it with New).
- Enter the Subsidy amount, in euros.
- Read the depreciation schedule on the right and click Save.
Worked example · Boulangerie Dupont SRL
Suppose the €32,000.00 van receives an investment grant of €4,800.00 (15% of its value).
In 2027, the van is depreciated by €5,333.30 (ten months): Fiplan releases €800.00 of the subsidy to income; in 2028, a full year, €960.01. At 31 December 2027, €4,000.00 of subsidy remains on the liabilities side.
Pitfalls
15… account, and Fiplan refuses to save one (decision V-14): a subsidy is entered in the Subsidy amount field of the investment it finances. A 15… line entered earlier stays in the plan, flagged [D249]: it is never released to income. Move its amount to the investment, then delete it.What it changes · 2027
Source
Art. 3:71 of the Royal Decree implementing the Companies and Associations Code (AR CSA / KB WVV; cited in the code): capital subsidies are released to income at the rate of depreciation of the fixed assets they finance.
Minimum standard chart of accounts (plan comptable minimum normalisé / minimumindeling van een algemeen rekeningenstelsel): accounts 15 (capital subsidies), 753 (capital and interest subsidies).
Fiplan convention (journal-engine.ts): each month's release equals its depreciation charge multiplied by the subsidy and divided by the depreciable base; the month in which the asset is fully depreciated releases the whole remaining balance of the subsidy.