
Disallowed expenses (DNA)
An expense in the accounts is not always deductible: part of it can be a “disallowed expense” (dépense non admise / verworpen uitgave). The accounting profit does not change; the tax does. Fiplan adds back the share you declare.
What it is for
On a General Expenses line, the DNA - Non-deductible expense (%) field says what share of the expense is not deductible. The expense stays whole in the income statement; Fiplan adds this share to profit before tax to calculate the taxable base for corporate income tax (impôt des sociétés / vennootschapsbelasting). The percentage is yours: Fiplan does not suggest one.
Steps
- Open Encoding, then General Expenses, and the expense line.
- Enter the DNA - Non-deductible expense (%).
- Click Save. The tax summary of the Encoding screen shows the disallowed expenses of the financial year.
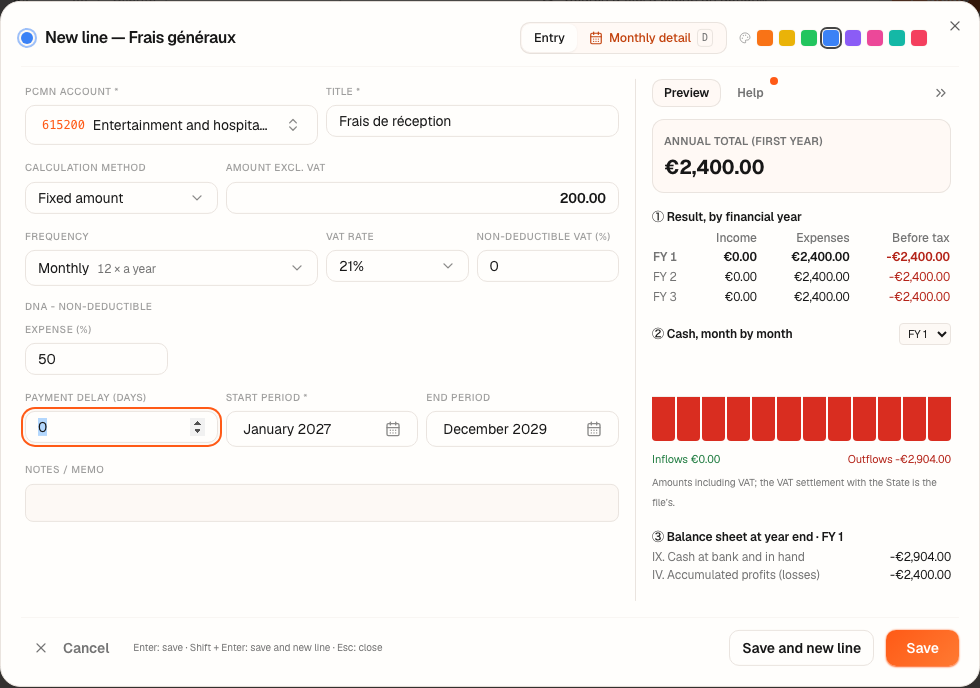
Worked example · Boulangerie Dupont SRL
Suppose reception costs of €200.00 per month, entered with 50% DNA (VAT left at 0% for the example). In 2027:
| Amount | |
|---|---|
| Expense for the financial year | 2,400.00 |
| Profit before tax (EBT) | 101,701.51 |
| Disallowed expenses added back | 1,200.00 |
| Taxable base | 102,901.51 |
| Corporate income tax | 20,725.38 |
The expense reduces the tax, and the add-back takes part of that reduction back: in total, the 2027 corporate income tax changes by -€300.00.
Pitfalls
What it changes · 2027
Source
Fiplan convention (recapitulatif-fiscal.ts, tax-bridge.ts): a line's DNA equals its expense for the financial year multiplied by the percentage entered; the taxable base is profit before tax plus the DNA. The percentage applicable to each expense is governed by the Income Tax Code 1992 (CIR 92 / WIB 92) and is not suggested by Fiplan.