
Prior tax losses and the basket
A tax loss is not lost: it is carried forward against the profits of the following years. Fiplan deducts it from the plan's taxable base, financial year after financial year, with no time limit, within the limit of the “basket” (corbeille / korfbeperking).
What it is for
The Prior tax losses (optional) are declared when the file of an existing company is created, and can be corrected later through Correct the prior year (income statement, tax losses). A company being incorporated has none.
Each financial year, Fiplan sets these losses off against the taxable base:
- up to €1,000,000 of base, without limit;
- above that, on 70% of the excess only;
- without any limit for a small company (petite société / kleine vennootschap) during its first four taxable periods (périodes imposables / belastbare tijdperken).
What cannot be set off is carried forward to the next financial year. Losses are never set off against the disallowed expense on the benefit in kind of a car: it stays in the taxable base (art. 198, § 1, 9° and 9°bis ITC 92).
Steps
- When you create an existing company, enter the Prior tax losses (optional).
- To correct them later, open the file menu, then Correct the prior year (income statement, tax losses).
- At the bottom of the income statement, expand Tax assumptions used: the line “Pertes fiscales antérieures … imputées sur les bénéfices du plan” (prior tax losses … set off against the plan's profits) is there, and the PDF report repeats it. (Fiplan shows this message in French.)
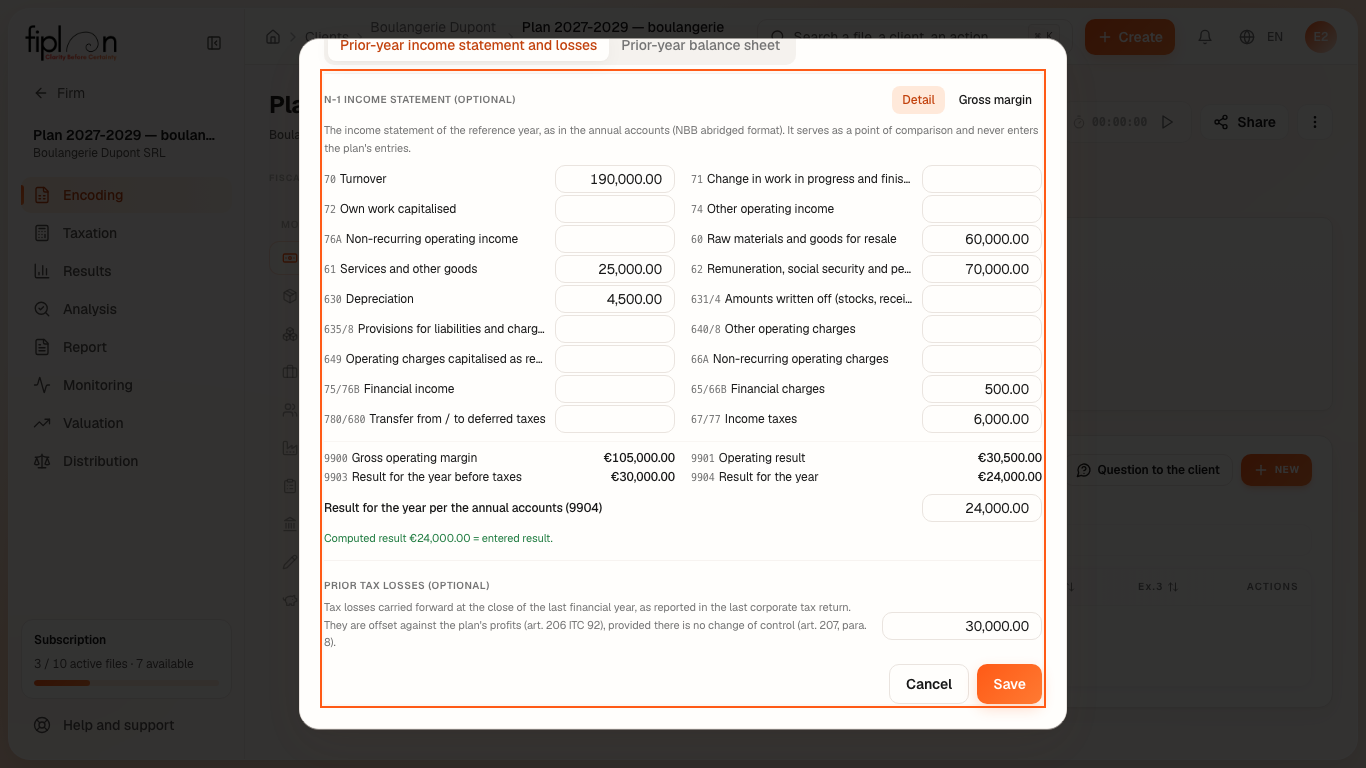
Worked example · Boulangerie Dupont SRL
Boulangerie Dupont is born in 2027: it has no prior losses. If it were an existing company carrying €30,000.00 of losses, Fiplan would set them off from 2027:
| 2027 | Amount |
|---|---|
| Taxable base before set-off | 104,101.51 |
| Losses set off | 30,000.00 |
| Taxable base | 74,101.51 |
| Corporate income tax (impôt des sociétés / vennootschapsbelasting), at the reduced rate | 14,820.30 |
That is €6,205.08 less tax. At the bottom of the income statement, the block “Tax assumptions used · 1” would write it as follows:
- Pertes fiscales antérieures de 30 000,00 € imputées sur les bénéfices du plan (art. 206 CIR 92) : reports repris sous réserve d’absence de changement de contrôle (art. 207, al. 8, CIR 92).
The basket only comes into play above one million: on a base of €1,500,000, the deduction would be capped at
Pitfalls
What it changes · 2027
Source
Art. 206 ITC 92: prior losses are deducted with no time limit. Art. 207 ITC 92: the basket, €1,000,000 plus 70% of the excess (para. 5); no limit for a small company during its first four taxable periods (para. 6); the extinction of losses in the event of a change of control (para. 8). Federal Public Service Finance (SPF Finances / FOD Financiën), explanatory notes to the corporate income tax return, tax year 2026 (docs/references/fiscal/SOURCES.md, R7, R8, R11, R12).