
The tax assumptions retained
A tax calculated on assumptions must state them. On screen, Fiplan separates what is to be known, at the bottom of the income statement, from what is to be corrected, in the plan checks. The report keeps every line.
What it is for
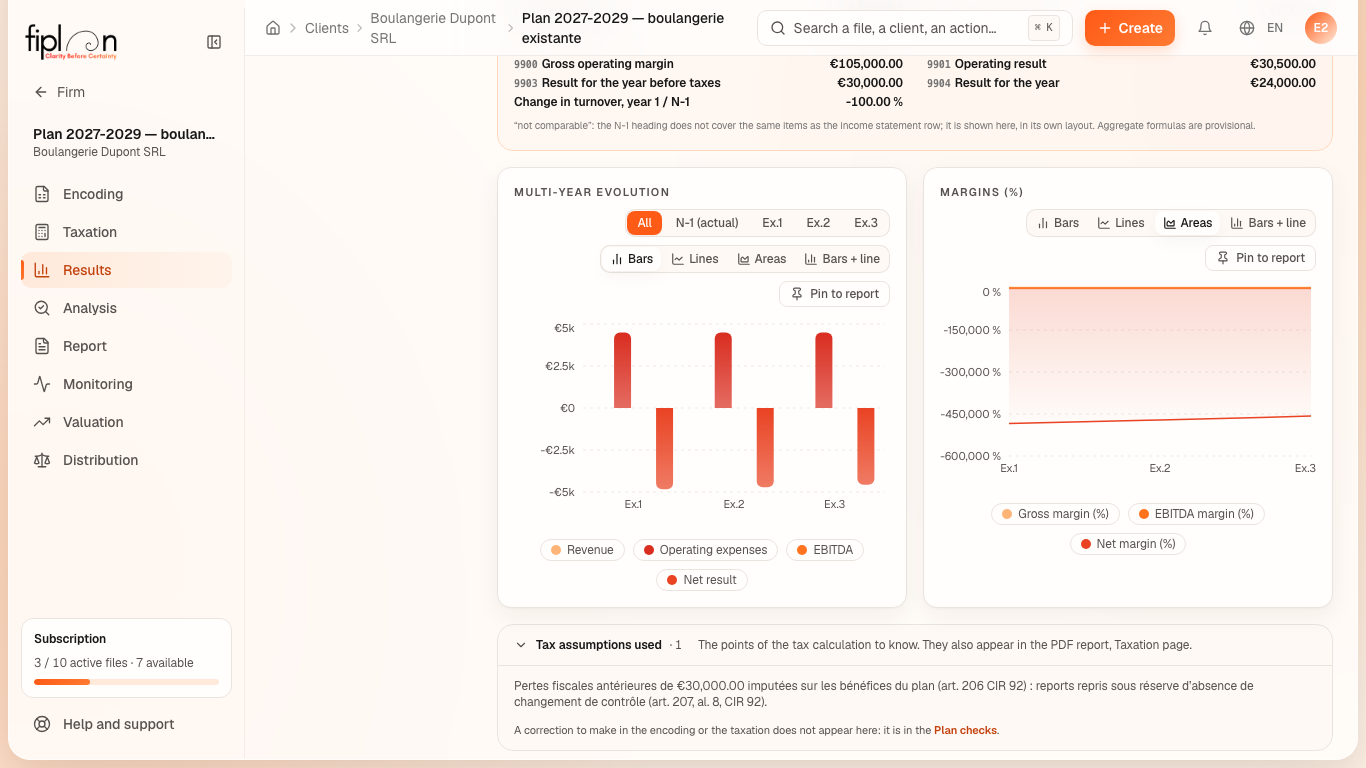
At the bottom of the Income Statement tab, below the charts, a grey collapsed block is headed Tax assumptions used, followed by its number of lines (“· n”), with this subtitle: “The points of the tax calculation to know. They also appear in the PDF report, Taxation page.” It only appears when it has at least one line. It only contains what is to be known; what needs a correction is a check to review in the checks badge. The PDF report (Taxation page, or Assumptions when the template has no Taxation page) and the Excel file write every line, each on one line, without a box:
| Line | When it appears | On screen | In the PDF and Excel |
|---|---|---|---|
| The financial year of non-standard length | a financial year does not last twelve months | at the bottom of Results | “Tax assumptions retained” block |
| Advance tax payments (versements anticipés / voorafbetalingen) of a financial year ≠ 12 months | same | at the bottom of Results | same |
| Prior tax losses | they are set off in the plan | at the bottom of Results | same |
| The provisional remuneration threshold | it decides reduced-rate eligibility | at the bottom of Results | same |
| Tax not calculated | the file is that of an individual or of a non-profit association (ASBL / vzw) | at the bottom of Results | same |
| The surcharge for insufficient advance payments | a net surcharge is due | at the bottom of Results, under its heading | PDF: “Advance payments (AP)” table; Excel: tax sheet — the surcharge line |
| The reduced rate subject to a reservation, and the summary per financial year | a condition of Article 215 of the Income Tax Code 1992 (CIR 92 / WIB 92) is not answered, or a financial year is not fully eligible | “SME reduced-rate eligibility” check | “Tax assumptions retained” block |
| The date of incorporation is unknown | the client's record does not show it | “Company incorporation date” check | same |
| Declining-balance depreciation | an old line still uses it | “Straight-line depreciation of assets” check | same |
| The subsidy entered on account 15 | an old line of Financing & contributions | “Capital subsidies” check | same |
| The property lease without a land value | the land value is not filled in | “Property leases: land value” check | same |
| The incorporation finding | an incorporation created before the Companies Code check | “Incorporation compliant with the CCA” check | same |
Steps
- Open Results, Income Statement tab, and scroll below the charts.
- Click Tax assumptions used to expand the block and read its lines.
- For a correction, follow the Plan checks link, at the foot of the block: the checks panel opens; answer the conditions in the Taxation tab, or complete the client's record.
- Generate the report: all remaining lines appear in it.
Worked example · Boulangerie Dupont SRL
The bakery's plan carries 2 tax assumptions, as the report writes them:
- Exercices 1 à 3 : taux réduit appliqué SOUS RÉSERVE · (b) Rémunération dirigeant — Périodes imposables 1 à 3 sur les 4 premières depuis la constitution — condition non applicable (art. 215 CIR 92) · Règles fiscales appliquées : EI 2028 à 2030.
- ISOC au taux réduit (art. 215 CIR 92), sous réserve des conditions (a) et (c) non renseignées. Sans ce taux : +5 000,00 € par exercice, soit +15 000,00 € sur l'horizon du plan.
These are two corrections: on screen, they are in the “SME reduced-rate eligibility” check, and the bottom of the income statement shows no block (0 lines). Once conditions (a) and (c) are answered, 0 remain in the report.
If the bakery were an existing company carrying €30,000.00 of prior tax losses, the bottom of the screen would show “Tax assumptions used · 1”, and, once expanded:
- Pertes fiscales antérieures de 30 000,00 € imputées sur les bénéfices du plan (art. 206 CIR 92) : reports repris sous réserve d’absence de changement de contrôle (art. 207, al. 8, CIR 92).
(Fiplan writes these lines in French, whatever the screen language.)
Pitfalls
What it changes · 2027
Source
Fiplan convention (reserves-fiscales.ts): a single function writes the lines for the screen, the PDF and the Excel file; an identical reservation over consecutive financial years is written once. A table with no default case (RANGEMENT_HYPOTHESES) says where the screen shows each line: at the bottom of Results, or in a check (financial-controls.ts); the PDF keeps every line. The surcharge is read from the engine's amounts (lignesMajorationVa).