
Advance tax payments and the surcharge
Corporate income tax (impôt des sociétés / vennootschapsbelasting) is paid in advance, in four advance tax payments (versements anticipés / voorafbetalingen); otherwise, it is increased by a surcharge (majoration / vermeerdering). Fiplan calculates this surcharge at the rate of the tax year (exercice d'imposition / aanslagjaar), deducts the credit (avantage / voordeel) earned by each payment, and adds the rest to the tax.
What it is for
In the Taxation tab, the Advance payments (AP) switch says whether the company pays its tax in advance, and what share per quarter (25% each by default). Fiplan then calculates, for each financial year:
- the gross surcharge: the financial year's tax × the surcharge rate of its tax year;
- the credits: each payment × its credit rate, which is higher for the earlier payments;
- the net surcharge: the gross surcharge minus the credits, never negative, added to the tax.
A small company (petite société / kleine vennootschap) pays no surcharge during its first three financial years since its incorporation.
Steps
- Open the Taxation tab, Corporate Tax (CIT) section.
- Leave Advance payments (AP) switched off, or switch it on and spread the Share of tax paid per quarter.
- Click Save tax parameters.
- At the bottom of the income statement, expand Tax assumptions used: a surcharge that is due is read there under the heading Surcharge for insufficient advance payments · art. 218 ITC 92, one line per financial year.
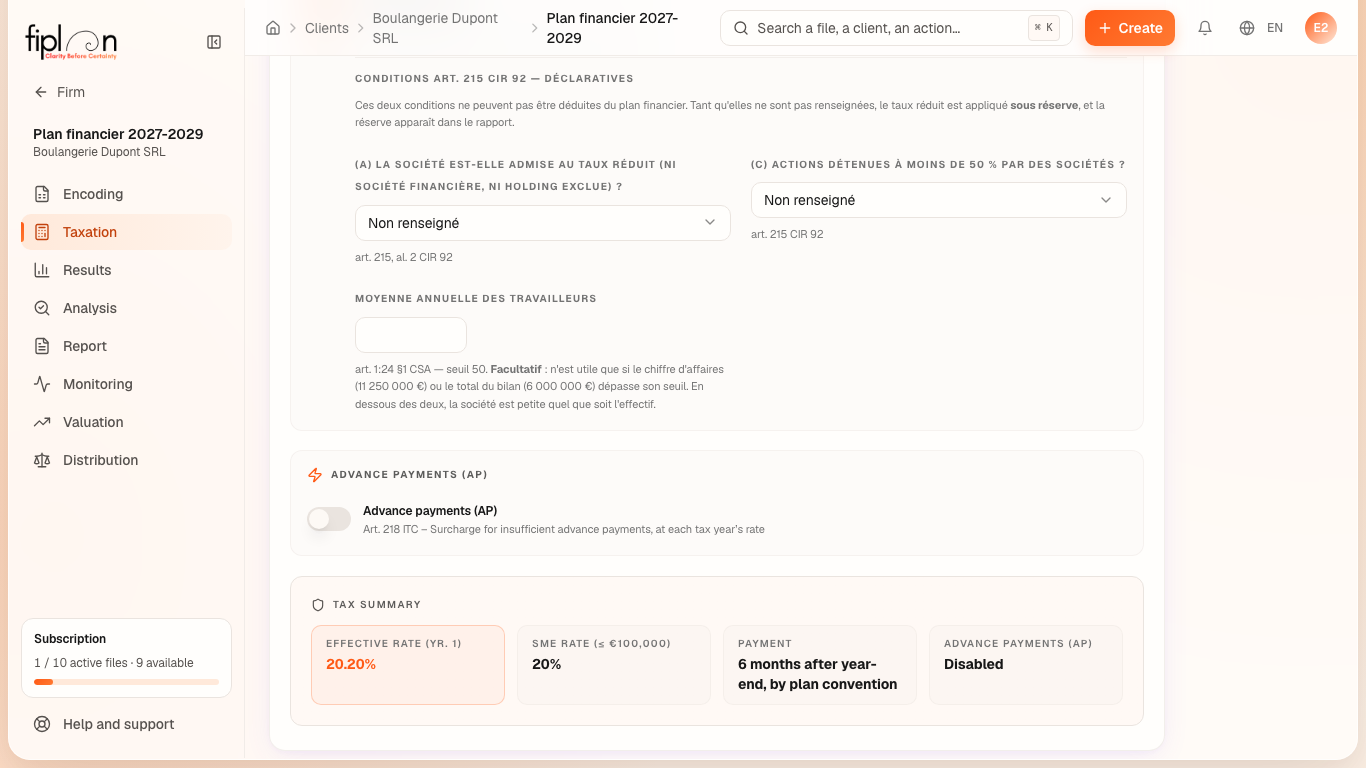
Worked example · Boulangerie Dupont SRL
The bakery is a small company in its first 3 financial years: Fiplan exempts it, no surcharge is added to its tax, and the bottom of the income statement shows none.
If it were not exempt, on the 2029 tax (€20,181.35), at a surcharge rate of 6.75%:
| Situation | Gross surcharge | Credits | Net surcharge |
|---|---|---|---|
| No advance payment | 1,362.24 | 0.00 | 1,362.24 |
| 25% per quarter (€5,045.34 each) | 1,362.24 | 1,362.24 | 0.00 |
The credits of the four payments are worth 9%, 7.5%, 6% and 4.5% of their amount: four quarters of the tax exactly offset the surcharge.
With no payment, the bottom of the income statement would write, under its heading:
- Yr 3: base €20,181.35 · overall rate 6.75% · gross €1,362.24 − benefits €0.00 = net surcharge €1,362.24
followed by a piece of advice: increase the advance payments, VA1 and VA2 first, which carry the highest credit.
Pitfalls
What it changes · 2027
Source
Art. 218 of the Income Tax Code 1992 (ITC 92; CIR 92 / WIB 92): the surcharge for insufficient advance payments; para. 2: no surcharge for a small company over its first three financial years since its incorporation.
Federal Public Service Finance (SPF Finances / FOD Financiën), “Versements anticipés” page (advance payments), tax year 2027: surcharge rate of 6.75%; credits of 9%, 7.5%, 6% and 4.5% (recorded in docs/references/fiscal/SOURCES.md, R18d, R19d, R20).