
VAT in the plan — regimes and parameters
For a standard VAT taxpayer (assujetti ordinaire / gewone btw-plichtige), the VAT charged and the VAT paid are set off against each other in each VAT return (déclaration TVA / btw-aangifte). For a business that does not charge VAT, the VAT on its purchases is a cost. The regime is set once, in the Taxation tab.
What it is for
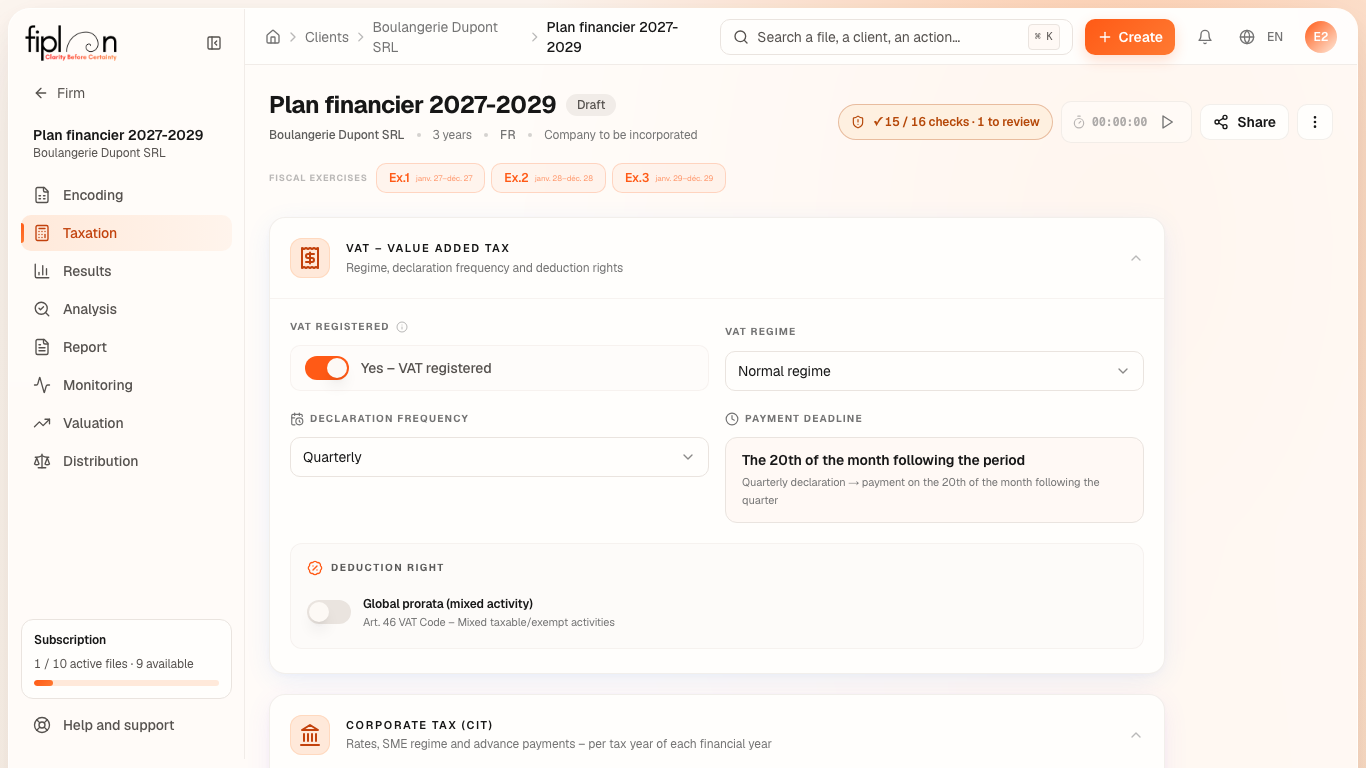
The VAT – Value Added Tax section of the Taxation tab holds:
- VAT registered; the VAT regime: normal regime, franchise (small business; franchise / vrijstellingsregeling) or exempt (art. 44);
- for the normal regime, the Declaration frequency — monthly or quarterly — and the Global prorata (mixed activity).
Depending on this regime, Fiplan treats the VAT of the lines entered as follows:
| Status | VAT on sales | VAT on purchases |
|---|---|---|
| Standard VAT taxpayer | charged, paid over to the State | recovered |
| Mixed activity (pro rata) | charged, paid over to the State | recovered pro rata; the rest is a cost |
| Franchise, exempt, not subject to VAT | none | a cost: it is added to the expense or to the price of the asset |
Steps
- Open the Taxation tab, VAT – Value Added Tax section.
- Choose the status and the regime.
- Under the normal regime, choose the frequency and, for a mixed activity, the pro rata.
- Click Save tax parameters.
Worked example · Boulangerie Dupont SRL
The bakery is a standard VAT taxpayer, with quarterly returns (the default). In 2027, the VAT charged (€12,960.00) and the VAT recovered (€10,867.20, van included) leave a balance of €2,092.80 owed to the State for the year. In the first quarter, the van puts the return in credit: Fiplan has this credit refunded in June 2027.
Pitfalls
What it changes · 2027
Source
VAT Code (Code de la TVA / Btw-wetboek): deduction (art. 45), the general pro rata (prorata général / algemeen verhoudingsgetal) of a mixed taxpayer (art. 46), exemption (art. 44), the franchise scheme for small businesses (art. 56bis). Federal Public Service Finance (SPF Finances / FOD Financiën), “Déclaration périodique TVA” (periodic VAT return) and “Nouvelle chaîne TVA” (the new VAT chain) (payment and refund deadlines).
Fiplan convention (vat-admin.ts): the status is derived from the file's parameters; without parameters, a standard VAT taxpayer.