
Cash, financial year by financial year and month by month
A profitable business can run short of money in a given month. Fiplan's monthly cash flow shows what the bank account will hold at the end of each month, and warns you if the balance falls below zero.
What it is for
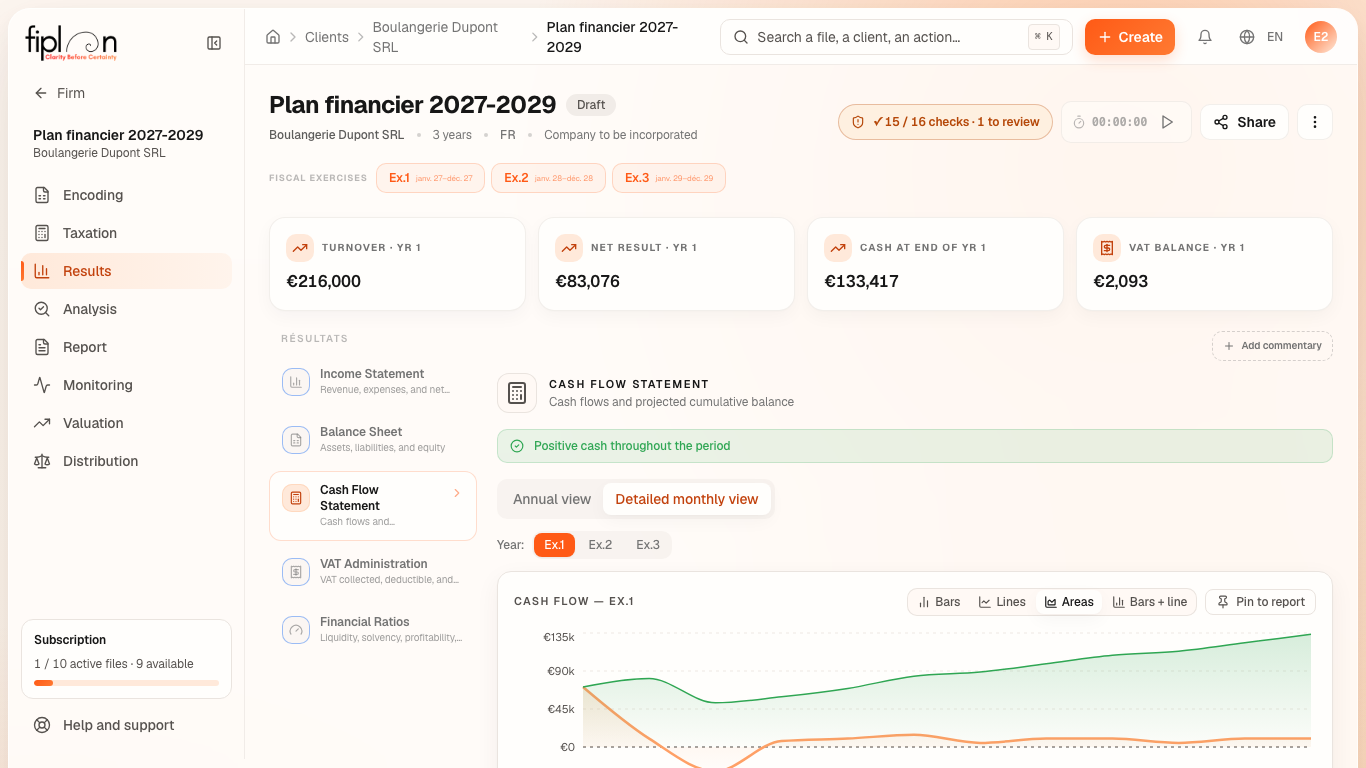
The Cash Flow Statement tab has two views. The Annual view splits each financial year's flows between operations, investments and financing — each including VAT —, then VAT settled with the State, advance tax payments (versements anticipés / voorafbetalingen) and the balance of the tax. The Detailed monthly view shows, for one financial year, each month: receipts, disbursements, net flow and cumulative balance.
At the top, the screen shows “Positive cash throughout the period”, or the number of negative months and the lowest point.
Steps
- Open Results, Cash Flow Statement tab.
- Read the alert: positive cash, or negative months and lowest point.
- In the Annual view, compare the three families of flows.
- Switch to the Detailed monthly view and choose the Year: the detailed table shows, month by month, customer receipts, then disbursements (supplies, general expenses, remuneration), investments, financing, VAT settled with the State and the tax.
Worked example · Boulangerie Dupont SRL
| Annual view | 2027 | 2028 | 2029 |
|---|---|---|---|
| Operating cash flow | 118,703.36 | 115,588.85 | 115,938.20 |
| Investing cash flow | -38,720.00 | 0.00 | 0.00 |
| Financing cash flow | 53,322.82 | -7,604.69 | -7,954.04 |
| VAT administration | 110.40 | -8,812.80 | -8,812.80 |
| Corporate income tax — balance | 0.00 | -21,025.38 | -20,094.01 |
| Net cash flow | 133,416.58 | 78,145.98 | 79,077.35 |
| Cumulative cash | 133,416.58 | 211,562.56 | 290,639.91 |
In 2027, financing includes the contribution (apport / inbreng) of €20,000.00 and the loan of €40,000.00, minus the capital repaid. The previous year's tax is paid in 2028 and 2029, on its own line: Corporate income tax — balance. The VAT on a sale or purchase paid in cash stays on the line of that operation; “VAT administration” only carries the returns paid to the State and the credits refunded.
The first three months of 2027:
| Month | Net flow | Cumulative balance |
|---|---|---|
| January | 71,121.34 | 71,121.34 |
| February | 9,958.36 | 81,079.70 |
| March | -28,761.64 | 52,318.06 |
March carries the van, VAT included: it is the lowest point of the plan, €52,318.06. No month is negative.
Pitfalls
What it changes · 2027
Source
Fiplan convention: flows are classified according to the journal entries that touch cash (account 550000) — operations, investment, financing (each including VAT), VAT settled with the State, advance tax payments, balance of the tax; a flow is classified first by the module of its line, then by its account; the cumulative balance of each month is the sum of the flows since the start of the plan.