
VAT administration
For an ordinary taxable person, VAT is neither income nor an expense: it passes through. Fiplan still follows it month by month, because it weighs on cash between the moment it is collected or paid and the moment it is declared.
What it is for
The VAT Administration tab shows three cards — VAT payable (total), VAT recoverable (total) and the balance — then an annual view and a monthly view. VAT returns (déclarations TVA / btw-aangiften) are monthly or quarterly, depending on the file's VAT settings (quarterly by default).
A file under the small business exemption scheme (franchise / vrijstellingsregeling), exempt (exempté / vrijgesteld) or not a taxable person (non assujetti / niet btw-plichtig) has no return: the tab says so, and the VAT paid on purchases becomes an expense or is added to the cost of the asset.
Steps
- Open Results, VAT Administration tab.
- Read the three cards, totalled over the financial years displayed.
- In the Annual view, read for each financial year the VAT on sales, the VAT on purchases, and the balance.
- In the Monthly view, follow the balance of each return.
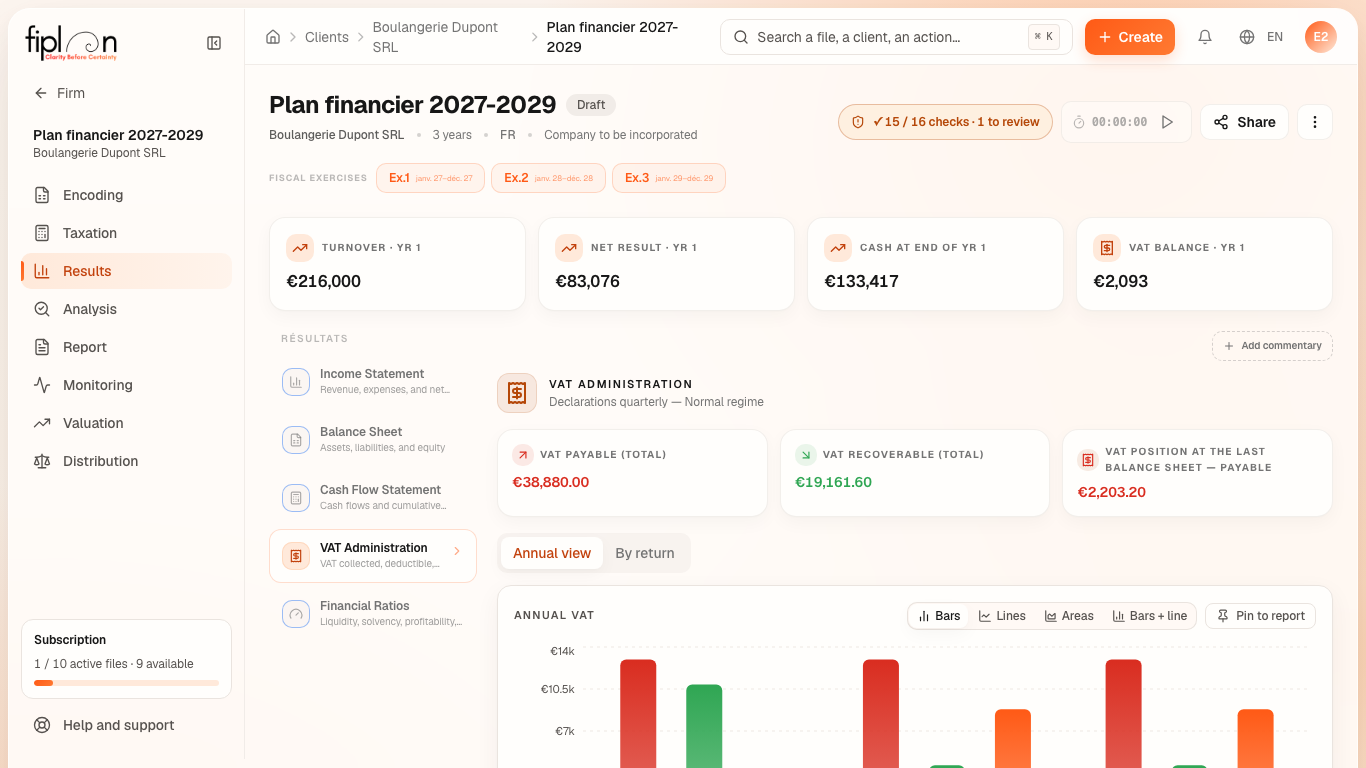
Worked example · Boulangerie Dupont SRL
The bakery files a return every quarter. In 2027:
| Return | VAT charged | VAT recoverable | Balance |
|---|---|---|---|
| 1st quarter | 3,240.00 | 7,756.80 | -4,516.80 |
| 2nd quarter | 3,240.00 | 1,036.80 | 2,203.20 |
| 3rd quarter | 3,240.00 | 1,036.80 | 2,203.20 |
| 4th quarter | 3,240.00 | 1,036.80 | 2,203.20 |
| 2027 | 12,960.00 | 10,867.20 | 2,092.80 |
In the first quarter, the VAT on the van (€6,720.00) exceeds the VAT on sales: the return shows a credit, which Fiplan has refunded in June 2027. The following quarters are payable: the balance for the second (€2,203.20) goes out in July 2027.
Pitfalls
What it changes · 2027
Source
VAT Code (Code de la TVA / Btw-wetboek): the deduction of VAT paid (Article 45); the pro rata of a mixed taxable person (assujetti mixte / gemengde belastingplichtige) (Article 46); the small business exemption scheme (Article 56bis); the exemption (Article 44). Federal Public Service Finance (SPF Finances / FOD Financiën), “Nouvelle chaîne TVA” (the new VAT chain): a credit is refunded two months after a monthly return, three after a quarterly one.
Fiplan conventions (journal-engine.ts, restitution-tva.ts): the balance due is paid in the month following the period; the refund is always requested; a small credit is carried forward.