
The distribution report
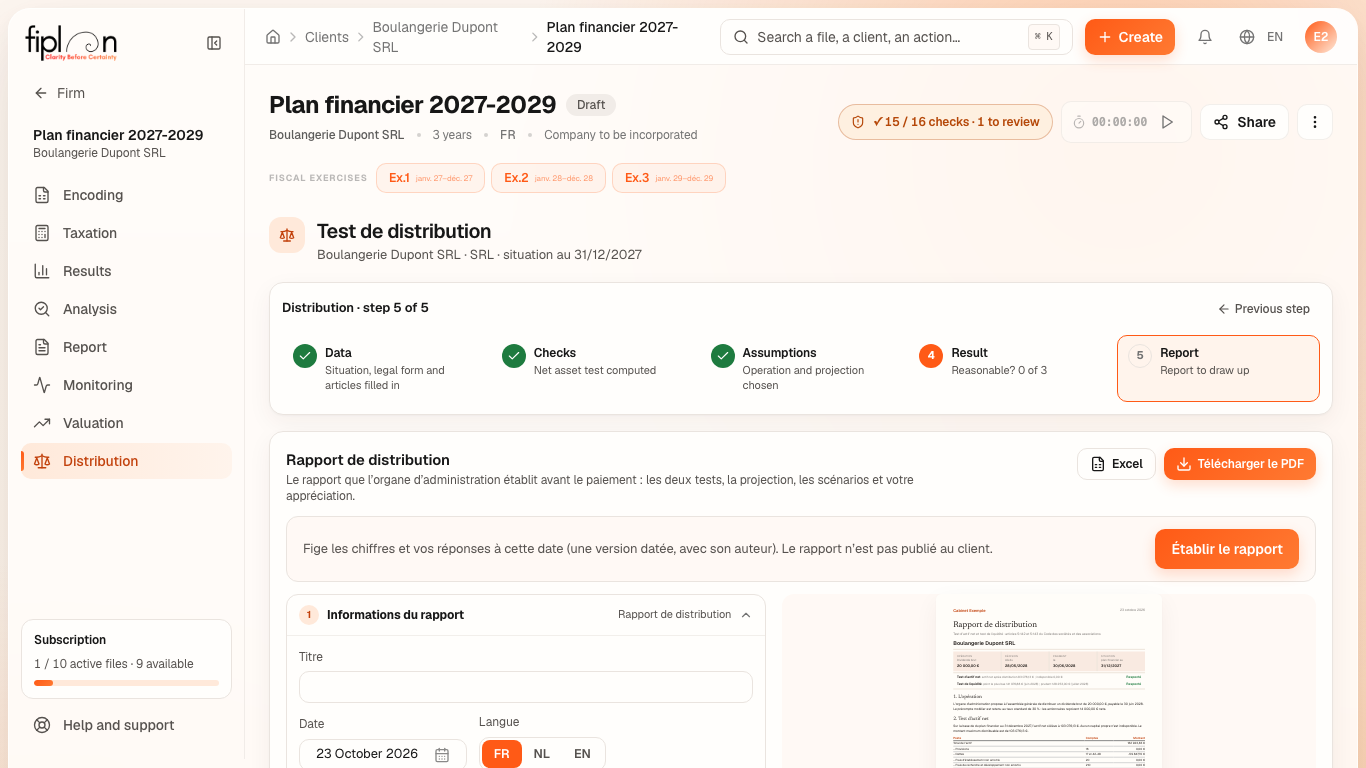
The distribution report takes up the whole test, in the chosen language, with its appendices: the cash table, the proposed entries and a template statement before payment. Once drawn up, it is frozen at its date; it is never published to the client.
What it is for
Step ⑤ “Rapport de distribution” lays out what steps ① to ④ calculated and what the firm judged. On the left, the settings; on the right, the PDF preview and its pages. The report has a summary (the operation, the decision, the payment, the position and the two verdicts), seven sections and three appendices; its subtitle cites the BCCA articles that apply to the company's legal form. The module's screen is in French; the report itself exists in French, Dutch and English.
| Section | Content |
|---|---|
| 1. The operation | the gross amount, the payment date, the withholding tax and the net |
| 2. Net asset test | the line-by-line calculation and the margin |
| 3. Liquidity ratios | quick ratio and current ratio, before and after |
| 4. Cash projection | the window of at least twelve months and the lowest point |
| 5. Scenarios | the scenarios chosen and their lowest points |
| 6. Reasonableness | the firm's three answers and their comments |
| 7. Conclusion | always included; the signatories |
Steps
- “Informations du rapport” (report information): the “Titre” (title), the “Date”, the “Langue” (language: French, Dutch or English) and the signatories: “Signé par” (signed by), “Nom” (name), “Qualité” (capacity), “+ Ajouter” (add).
- “Contenu du rapport” (report content): untick a section you do not want; the conclusion is always included.
- “Annexes” (appendices): the “Tableau de trésorerie mensuel” (monthly cash flow table; cells changed by hand are marked there, with their note), the “Écritures comptables proposées” (proposed accounting entries) and the “Modèle de constat avant paiement” (template of the statement before payment).
- “Mise en page et marque du cabinet” (layout and firm branding): the firm's colour and brand, as on the other documents.
- Reread the preview and its thumbnails, then “Télécharger le PDF” (download the PDF) or “Excel”.
- “Établir le rapport” (draw up the report): the figures and your answers are frozen at that date, in a dated version with its author. A later change to the test sets the report to “à revoir” (to review): “Établir une nouvelle version” (draw up a new version).
As long as no report is drawn up, the dashboard lists it under “To do”: Distribution report to draw up, with the company and the payment date.
Worked example · Boulangerie Dupont SRL
For the gross dividend of €20,000.00 paid on 30 June 2028, the proposed-entries appendix returns:
| Account | Debit | Credit |
|---|---|---|
| 694000 | 20,000.00 | 0.00 |
| 471000 | 0.00 | 20,000.00 |
| 471000 | 20,000.00 | 0.00 |
| 453000 | 0.00 | 6,000.00 |
| 550000 | 0.00 | 14,000.00 |
The decision (the dividend on 694000 against the debt to shareholders, 471000), then the payment: the withholding tax retained (€6,000.00, on 453000) and the net paid (€14,000.00, through the bank). These entries are proposed: they are entered in the profit appropriation, which writes them to the journal.
Pitfalls
What it changes · 2028
Source
The report, its sections and appendices: src/lib/distribution/rapport.ts (DISTRIBUTION-2); the proposed entries: generateAllocationEntries (src/lib/profit-allocation.ts), dividend on 694000, debt on 471000, withholding tax on 453000; withholding tax at the standard rate (tax sources R21). Tests: art. 5:142 and 5:143 (BV/SRL), 6:115 and 6:116 (CV/SC), 7:212 (NV/SA) of the BCCA. The template statement before payment is a practice of the workshop, to be reviewed by the auditor.