
Reading the balance sheet — simplified view and legal BNB view
The balance sheet says what the business owns and what it owes, on the last day of each financial year. Fiplan presents it in two ways — simplified, for a quick read, and legal, heading by heading of the BNB format — without ever changing an amount.
What it is for
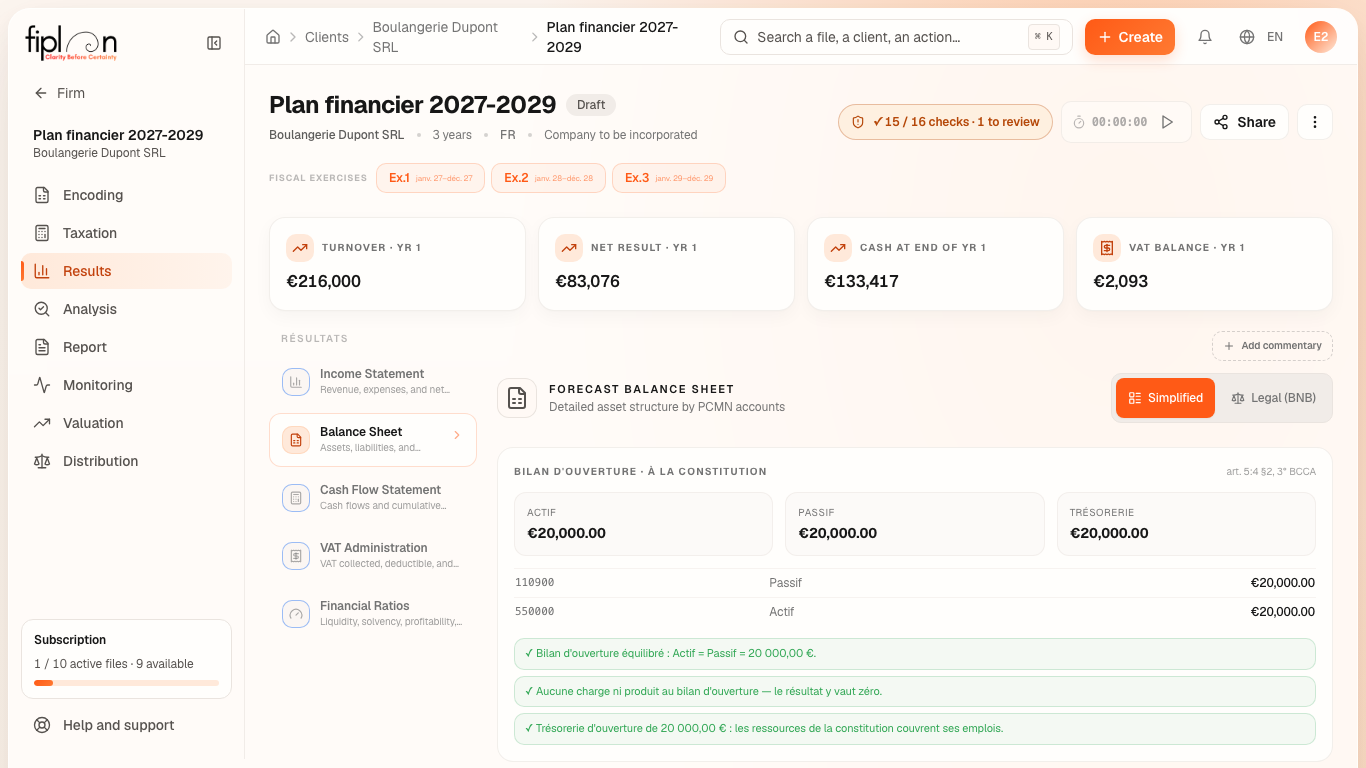
The Balance Sheet tab of Results shows two tables, ASSETS and LIABILITIES, one column per financial year. The Simplified / Legal (BNB) button changes the presentation: the simplified view groups the items (fixed assets, current assets, equity, long-term and short-term debt); the legal view unfolds the tree of the format of the National Bank of Belgium (BNB / NBB), from “I. Formation expenses” to “X. Deferred charges and accrued income”.
Below the tables, Fiplan checks the balance: assets = liabilities at each year-end, to the cent.
Steps
- Open Results, Balance Sheet tab.
- Choose the view: Simplified (default) or Legal (BNB).
- For an incorporation (constitution / oprichting), read the opening balance sheet block (bilan d'ouverture / openingsbalans); the screen shows its heading in French.
- Check the balance badges, “Year | Assets = Liabilities”.
- Open Balance Diagnostic (Debit/Credit) for the detail of the journal totals.
Worked example · Boulangerie Dupont SRL
The balance sheet of the running example, simplified view:
| ASSETS | 2027 | 2028 | 2029 |
|---|---|---|---|
| Fixed assets | 26,666.70 | 20,266.70 | 13,866.70 |
| of which van (242000) | 32,000.00 | 32,000.00 | 32,000.00 |
| of which accumulated depreciation (249000) | -5,333.30 | -11,733.30 | -18,133.30 |
| Stocks | 2,840.55 | 2,840.55 | 2,840.55 |
| Available cash | 133,416.58 | 211,562.56 | 290,639.91 |
| TOTAL ASSETS | 162,923.83 | 234,669.81 | 307,347.16 |
| LIABILITIES | 2027 | 2028 | 2029 |
|---|---|---|---|
| Contribution (apport / inbreng) | 20,000.00 | 20,000.00 | 20,000.00 |
| Profit carried forward (bénéfice reporté / overgedragen winst) | 83,076.13 | 163,358.17 | 243,902.22 |
| Equity | 103,076.13 | 183,358.17 | 263,902.22 |
| Loan, portion due after more than one year (173000) | 25,718.13 | 17,764.09 | 9,444.64 |
| Loan, portion due within one year (423000) | 7,604.69 | 7,954.04 | 8,319.45 |
| Corporate income tax (ISOC / VenB) payable (450000) | 21,025.38 | 20,094.01 | 20,181.35 |
| VAT payable (451000) | 2,203.20 | 2,203.20 | 2,203.20 |
| Withholding tax (précompte professionnel / bedrijfsvoorheffing, 453000) and social security (ONSS / RSZ, 454000) | 417.26 + 2,879.04 | 417.26 + 2,879.04 | 417.26 + 2,879.04 |
| TOTAL LIABILITIES | 162,923.83 | 234,669.81 | 307,347.16 |
The 2027 tax (€21,025.38) is still owed on 31 December: by convention, Fiplan pays it six months after the year-end.
Pitfalls
What it changes · 2027
Source
Royal Decree implementing the Companies and Associations Code (21 October 2018; AR CSA / KB WVV): the format of the annual accounts (comptes annuels / jaarrekening) filed with the National Bank (headings I to X of assets, I to V of equity, debts due after more than one year and within one year).
Fiplan convention (bilan-bnb.ts, bilan-simplifie.ts): each heading is the sum of the balances of its accounts in the journal; the simplified view groups the same headings.