
The opening balance sheet of an incorporation
The financial plan of a company to be incorporated presents its opening balance sheet. Fiplan builds it from the entries of the first month: the contribution, and whatever you mark as present from incorporation.
What it is for
In an incorporation file, the window of an investment, financing or receivable or debt line offers the In the opening balance sheet (at incorporation) switch (bilan d'ouverture / openingsbalans). When it is on, the line is an item of the company's assets and liabilities present from incorporation, before any operating transaction: its Start period is set to the first month of the plan.
An existing company has no opening balance sheet: what it owns comes in through its prior-year (N-1) balance sheet.
Steps
- Open the line (for example the loan, in Financing & Contributions).
- Turn on In the opening balance sheet (at incorporation): the Start period moves to the first month of the plan and is locked.
- Click Save.
- Read the opening balance sheet in Results, Balance Sheet tab, and in the report.
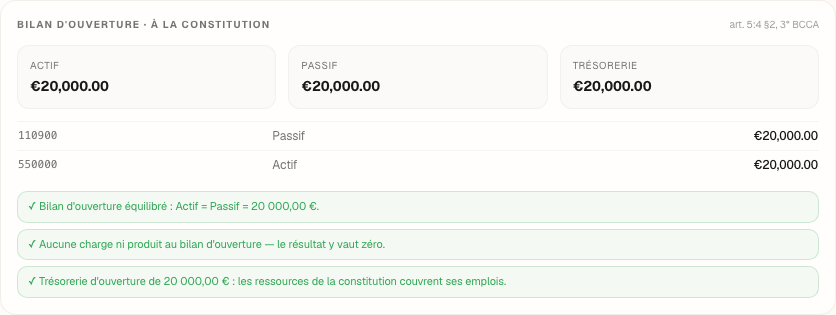
Worked example · Boulangerie Dupont SRL
Without marking anything, the bakery's opening balance sheet shows only the contribution: €20,000.00 of cash, €20,000.00 of contribution.
If the loan of €40,000.00 is taken out at incorporation and marked in the opening balance sheet, its funds received in the first month enter the starting balance sheet:
| Opening balance sheet | Assets | Liabilities |
|---|---|---|
| Cash | 60,000.00 | |
| Contribution | 20,000.00 | |
| Bank loan | 40,000.00 | |
| Total | 60,000.00 | 60,000.00 |
Pitfalls
What it changes · incorporation
Source
Companies and Associations Code (CSA / WVV), art. 5:4, § 2, 3° (SRL) — and 6:5, 7:3 for the SC and the SA: the financial plan includes an opening balance sheet.
Fiplan convention (bilan-ouverture.ts): the opening balance sheet is a cut of the journal at the first month, on the marked lines only, with no class 6 or 7.