
Allocating the result and the dividend
The result of a financial year belongs to no one until the general meeting has allocated it: it can go to the reserves, be distributed or be carried forward. Fiplan lets you decide, financial year by financial year, and checks that the distribution is allowed.
What it is for
The Profit Allocation module (affectation du résultat / resultaatbestemming) shows one block per financial year: its year-end, its status (100 % carried forward, Appropriated or Refused) and the Appropriate the result button. Without an allocation, the profit stays carried forward: it builds up in account 140000.
The window does not calculate the result: it reads it from the journal — Profit (loss) for the period available for appropriation, Profit (loss) brought forward from the previous period, and their sum, the Profit (loss) available for appropriation.
Steps
- Open Encoding, then Profit Allocation, and click Appropriate the result on the financial year you want.
- Check the Appropriated financial year and the Result to appropriate, prefilled with the calculated result.
- Split it: legal reserve (réserve légale / wettelijke reserve) (130), unavailable (131), tax-exempt (132), available (133), Dividende brut (471) (the gross dividend; the screen shows this field in French), directors' profit shares (tantièmes / tantièmes) (472). The rest is carried forward.
- If a dividend is planned: choose the Précompte mobilier (the withholding tax on dividends, précompte mobilier / roerende voorheffing; the screen shows this field in French) and, if needed, the Dividend payment date.
- Read the verdict — Distribution — and click Save.
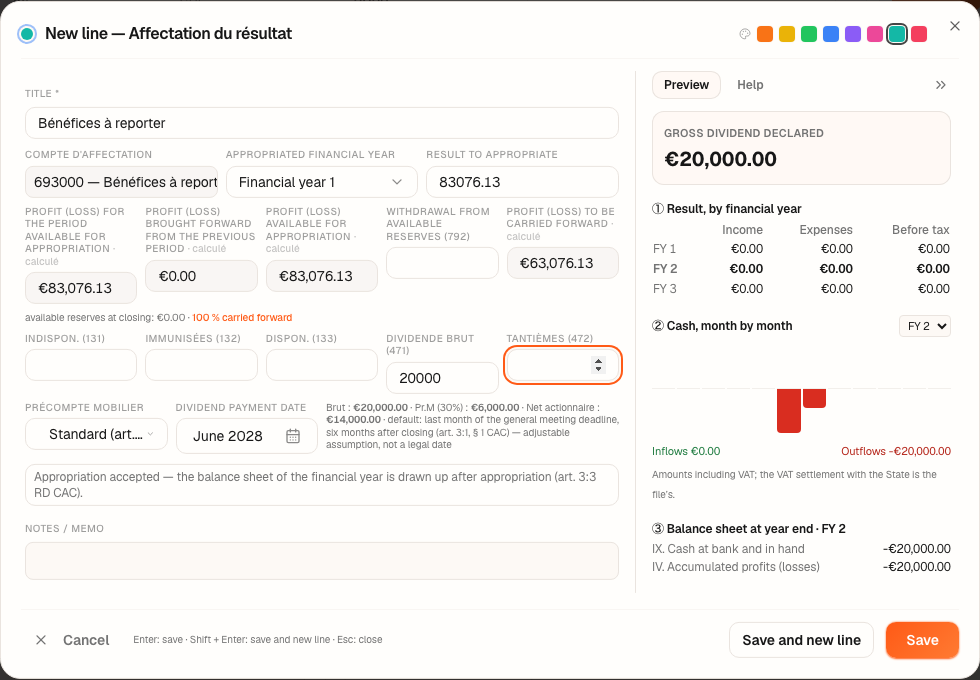
Worked example · Boulangerie Dupont SRL
The 2027 result is €83,076.13. The general meeting (assemblée générale / algemene vergadering) declares a gross dividend of €20,000.00 and carries forward the rest, €63,076.13.
| What Fiplan posts | Period | Debit | Credit | Amount |
|---|---|---|---|---|
| The dividend declared, at year-end | December 2027 | 140000 | 471000 | 20,000.00 |
| The withholding tax deducted | June 2028 | 471000 | 453000 | 6,000.00 |
| The net dividend paid | June 2028 | 471000 | 550000 | 14,000.00 |
| The withholding tax paid to the tax authorities | July 2028 | 453000 | 550000 | 6,000.00 |
The withholding tax is deducted at the standard rate of 30%, on the gross amount. By default, the payment falls in the sixth month after year-end, June 2028.
The two distribution tests for an SRL (société à responsabilité limitée / besloten vennootschap), as Fiplan reports them:
- Net assets (art. 5:142 of the Companies and Associations Code, CSA / WVV): conforme — net assets after distribution €83,076.13, unavailable amount €0.00 (the bakery's contribution is available).
- Liquidity (art. 5:143 CSA): conforme — over the twelve months after the payment, the lowest cash balance is €146,853.00, in July 2028.
(These two verdicts are status codes of Fiplan's engine, written in French.)
Pitfalls
What it changes · 2028
Source
Companies and Associations Code (CSA / WVV): the net asset test (art. 5:142 for the SRL, 6:115 for the SC, 7:212 for the SA) and the liquidity test (art. 5:143, 6:116); the legal reserve of an SA (art. 7:211); the general meeting within six months of year-end (art. 3:1, § 1). Royal Decree implementing the CSA (AR CSA / KB WVV), art. 3:3: the balance sheet drawn up after appropriation.
Withholding tax on dividends: 30% (Federal Public Service Finance page “Précompte mobilier” (withholding tax on dividends), SPF Finances / FOD Financiën, recorded in docs/references/fiscal/SOURCES.md, R21).
Fiplan conventions (affectation-exercice.ts): the payment in the last month of the general meeting's deadline, which can be changed; the withholding tax paid in the month after the payment.