
The N-1 income statement and tax losses
Comparing the plan with the last completed financial year is a banker's first reflex. The N-1 income statement is there for that comparison: it is not written to the journal.
What it is for
Two optional steps end the “Existing company — N-1 balance sheet” page.
5 · Results N-1 — the N-1 income statement (optional) block offers two modes: Detail (turnover, supplies, services and other goods, remuneration, depreciation…) or Gross margin (the gross operating margin, code 9900, instead of the first headings). Fiplan calculates the aggregates — 9900, 9901, 9903, 9904 — and compares the calculated result with the Result for the year per the annual accounts (9904) that you enter. The annual accounts (comptes annuels / jaarrekening) are those of the prior financial year (N-1). The Results screen then shows an “N-1 (actual)” column and the change in turnover; without this step, the plan says “N-1 income statement not carried forward”.
6 · Tax losses — the Prior tax losses (optional) field: the tax losses carried forward at the close of the last financial year, as reported in the last corporate tax return.
Both steps stay Optional while they are empty, and become Done once they are filled in.
Steps
- In step 5 · Results N-1, choose the mode: Detail or Gross margin.
- Enter the headings, then the result in the annual accounts (9904). Read the check line under the aggregates.
- If the company has tax losses carried forward from earlier years, enter them in step 6 · Tax losses.
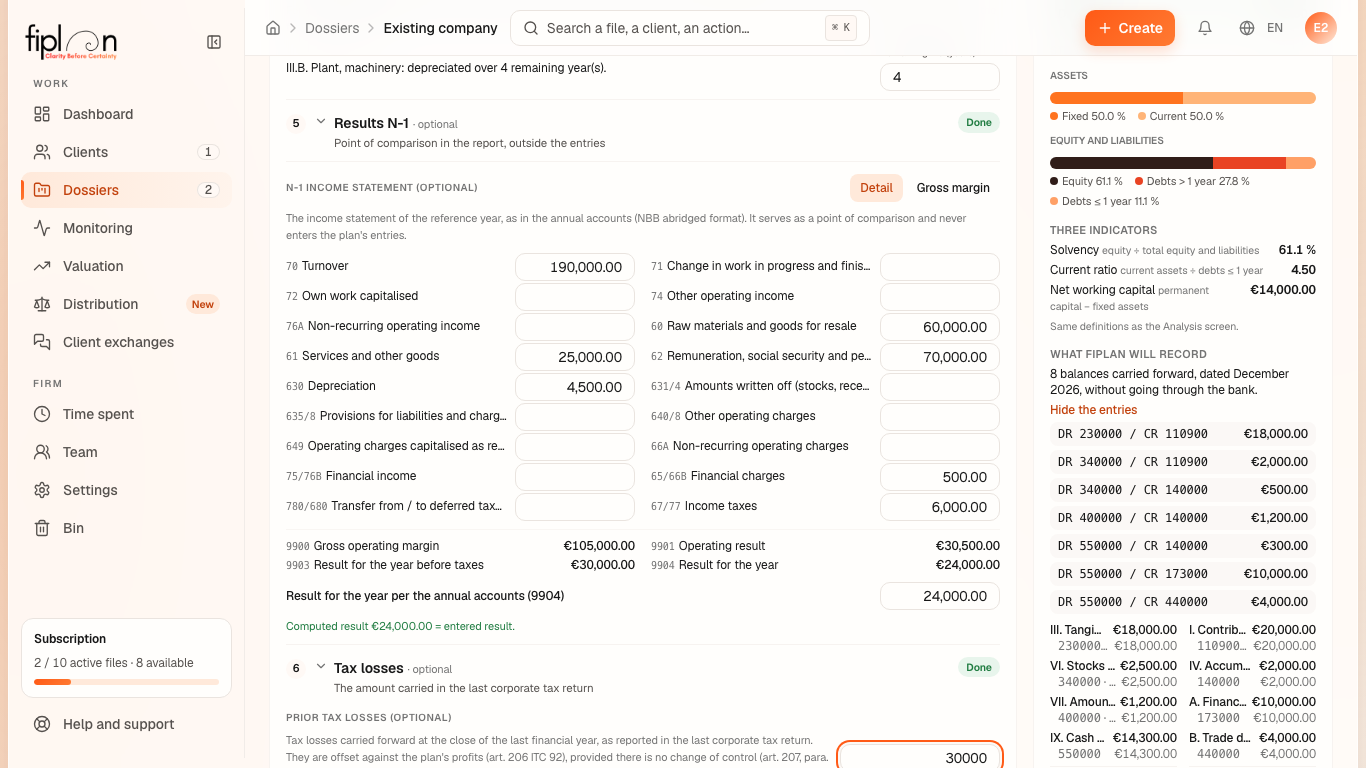
Worked example · Boulangerie Dupont SRL
The existing bakery enters its 2026 financial year:
| Code | Heading | Amount |
|---|---|---|
| 70 | Turnover | 190,000.00 |
| 9900 | Gross operating margin | 105,000.00 |
| 9901 | Operating result | 30,500.00 |
| 9903 | Result for the year before taxes | 30,000.00 |
| 9904 | Result for the year | 24,000.00 |
The result entered, €24,000.00, matches the calculated result: “Computed result €24,000.00 = entered result.” Entered as €23,900.00, it would be refused: “Computed result €24,000.00 ≠ entered €23,900.00: gap €100.00. The file cannot be created until the gap is zero.”
The plan's turnover, €216,000.00 in 2027, then grows by 13.68% compared with 2026.
Pitfalls
What it changes
Source
National Bank of Belgium (BNB / NBB), abridged format of the annual accounts: the headings and the codes 9900, 9901, 9903, 9904. The formulas of the aggregates are Fiplan's, on a provisional basis, and are on the reviewer's list.
Income Tax Code 1992 (CIR 92 / WIB 92), art. 206 and 207, para. 8, as the screen cites them: the offset of prior losses, subject to a change of control.
Fiplan convention (compte-resultats-n1.ts): the refusal of a result that does not match to the cent.