
Shareholder contributions
The contribution creates the equity. At incorporation, Fiplan posts it itself, from what you declare when you create the file; later on, an increase is entered as financing whose money is not repaid.
What it is for
The account of the contribution (apport / inbreng) depends on the client's Legal form: an SA (société anonyme / naamloze vennootschap) has share capital (100000); an SRL (société à responsabilité limitée / besloten vennootschap) or an SC (société coopérative / coöperatieve vennootschap) has a contribution outside capital (apport hors capital / inbreng buiten kapitaal), either available (110900) or made unavailable by the articles of association (statuts / statuten) (111900). In Financing & Contributions, a 100, 101 or 11… account is recognised as an Equity contribution: no repayment, no interest.
Steps
- At incorporation: declare the contribution when you create the file — the cash contribution (subscribed, paid up, libéré / volgestort), the Contributions in kind (one row per asset: Account, Contributed asset, Value, Life) and, in Founders & contributions, each founder's contribution: the Total contributions row adds up cash and kind, and the founders' table must reach that total. Fiplan itself writes the lines and the opening balance sheet — see Creating a file.
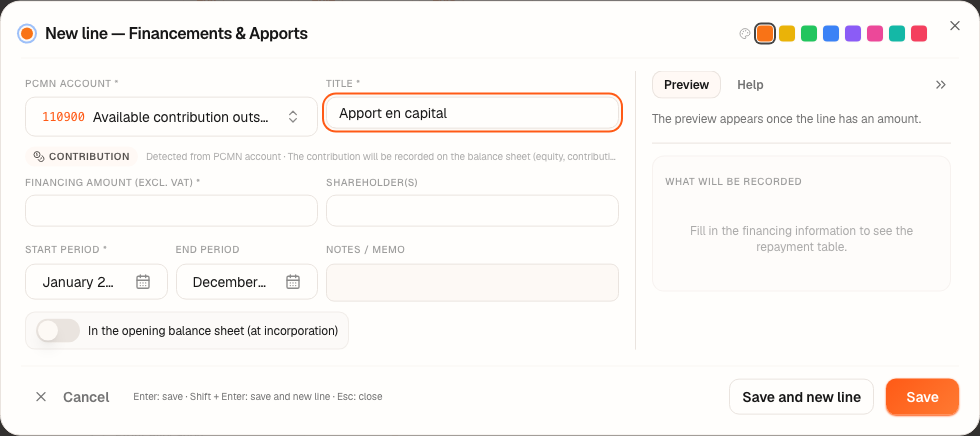
- Later on: open Encoding, then Financing & Contributions, and click New.
- Choose the contribution's PCMN Account (Belgian minimum chart of accounts, PCMN / MAR), which Fiplan proposes according to the client's form, and a Title.
- Enter the Financing amount (excl. VAT) and, in Shareholder(s), the shareholder's name.
- Choose the Start period — the month the money comes in — and click Save.
Worked example · Boulangerie Dupont SRL
Boulangerie Dupont is incorporated with a contribution of €20,000.00, fully paid up: Fiplan posts an inflow of €20,000.00 to the bank, against account 110900.
If Marie Dupont had paid up only €10,000.00 of the €20,000.00 subscribed, Fiplan would post two entries in the month of incorporation:
| Entry | Debit | Credit | Amount |
|---|---|---|---|
| The paid-up part, paid into the bank | 550000 | 110900 | 10,000.00 |
| The uncalled part (partie non appelée / niet-opgevraagd gedeelte) | 110901 | 110900 | 10,000.00 |
The opening balance sheet would then show only €10,000.00 of equity, and the same amount of cash.
And if, in addition to €20,000.00 in cash, she contributed in kind a dough mixer worth €6,000.00, depreciated over 5 years: the dough mixer enters the assets in account 232000 with no movement in the bank, and the opening balance sheet totals €26,000.00, including €20,000.00 of cash.
When the file is created, the screen says so: Total contributions — €20,000.00 in cash + €6,000.00 in kind = €26,000.00. Marie Dupont, the sole founder, then contributes €26,000.00: her share is 100%, and the check line confirms “The founders’ contributions equal the total contributions”. Had her contribution stayed at €20,000.00, creation would wait: “Missing: allocate €6,000.00 among the founders”.
Pitfalls
What it changes · incorporation
Source
Companies and Associations Code (CSA / WVV): the SRL and the SC have no capital (art. 5:3, 6:3); the SA has capital (art. 7:2).
Opinion 2019/14 of the Belgian Accounting Standards Commission (avis CNC / CBN-advies; accounting treatment of contributions in a company without capital): available or unavailable contribution outside capital; uncalled part tracked in a sub-account (§ 12-13). Accounts 110900, 110901, 111900 and 111901 are Fiplan subdivisions.
Minimum standard chart of accounts: accounts 100 (subscribed capital), 101 (uncalled capital), 11 (contribution outside capital), 23 (plant, machinery and equipment).
Fiplan convention, declared in the code (creation-dossier.ts, tableauFondateurs and refusFondateurs): the founders' contributions equal the total contributions, to the cent; each founder's share = their contribution ÷ the founders' total contributions.