
The director's remuneration
The remuneration of a director (administrateur / bestuurder) is not a salary: it is entered in the Remuneration module, on an account 6181, with its own form. It counts twice in the plan: as an expense, and as a condition for the reduced rate (taux réduit / verlaagd tarief) of corporate income tax (impôt des sociétés / vennootschapsbelasting).
What it is for
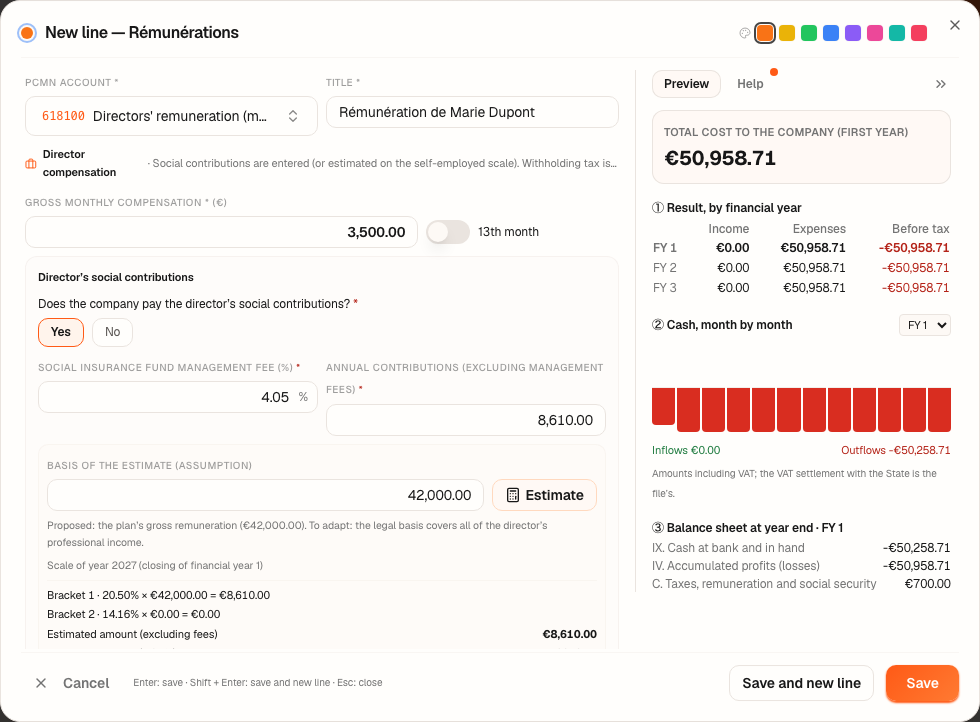
As soon as the chosen PCMN Account — the account in the Belgian minimum chart of accounts (PCMN / MAR) — starts with 6181 (remuneration of a director's mandate), the window replaces the salaried employee's form with the form for a company director (dirigeant d'entreprise / bedrijfsleider): Director compensation. The gross amount you enter is the company's expense; Fiplan derives from it the payroll withholding tax (précompte professionnel / bedrijfsvoorheffing) to be withheld and the net amount to be paid.
The director's remuneration is also read by the tax calculation: it is one of the conditions of the corporate income tax reduced rate (Article 215 of the Income Tax Code 1992, CIR 92 / WIB 92) — see Corporate income tax and the reduced rate.
Steps
- Open Encoding, then Remuneration, and click New.
- Choose the PCMN Account
618100— directors' remuneration (mandate) — and a Title. - Enter the Gross monthly compensation, and tick 13th month if one is planned.
- Answer the social contributions question (see The director's social contributions), then open Adjust the withholding tax to check the Withholding tax, proposed by default.
- If the company grants a benefit in kind, open the Benefits in kind (valued at a flat rate) block, folded as long as no amount is entered: the benefit's annual amount, financial year by financial year, under Car or Other (housing, loan, options…). For a car, answer Does the company pay for the fuel?: saving waits for the answer. On the right, the Directors’ benefits in kind frame gives, for each financial year, their share of the remuneration and the limit.
- Check the periods, read the Monthly breakdown – Director on the right and click Save. If the company pays the contributions, Fiplan also creates the line “Social contributions – …” (account 618200).
Worked example · Boulangerie Dupont SRL
Marie Dupont, a director, pays herself €3,500.00 gross per month from January 2027, i.e. €42,000.00 per financial year on account 618100.
| What Fiplan posts, each month | Debit | Credit |
|---|---|---|
| The withholding tax deducted | 618100 | 453000 |
| The rest of the gross amount, paid to the director | 618100 | 550000 |
| The withholding tax paid over, the following month | 453000 | 550000 |
January's withholding tax is therefore paid in February 2027; December 2027's (€700.00) remains a debt on the balance sheet at 31 December and is paid in January 2028.
For the corporate income tax reduced rate, Fiplan displays for 2027: “(b) Rémunération dirigeant — Période imposable 1 sur les 4 premières depuis la constitution — condition non applicable (art. 215 CIR 92)”. (Fiplan shows this message in French.) Boulangerie Dupont is incorporated on 4 January 2027: its first four taxable periods (périodes imposables / belastbare tijdperken) are not subject to this condition.
If the company also made a car available to Marie Dupont — a benefit valued by the accountant at €3,000.00 a year, fuel paid by the company —, Fiplan would read for 2027:
| Benefits in kind · 2027 | Amount |
|---|---|
| The benefit entered (car) | 3,000.00 |
| Total remuneration: the remuneration and the benefit | 45,000.00 |
| The limit: 20% of total remuneration | 9,000.00 |
| The disallowed expense: 40% of the benefit | 1,200.00 |
The benefit weighs 6.7% of total remuneration: below the limit, the reduced rate is not refused for that reason. The disallowed expense is added to the corporate income tax base, and stays there even at a loss (no loss or deduction absorbs it); without fuel paid, it would be €510.00 (17%). The benefit itself writes nothing to the journal.
The director's social security contributions (account 618200) have their own article: The director's social contributions.
Pitfalls
620… account opens the salaried employee's form (NSSO, ONSS / RSZ; double holiday pay, double pécule de vacances / dubbel vakantiegeld); only a 6181… account opens the director's form.What it changes · 2027
Source
Minimum standard chart of accounts (plan comptable minimum normalisé / minimumindeling van een algemeen rekeningenstelsel, annex 1 to the Royal Decree of 21 October 2018): account 618 (directors' remuneration), account 453 (taxes withheld). Account 618100 and its subdivision 618200 are Fiplan accounts.
Article 215 of the Income Tax Code 1992: the remuneration condition of the reduced rate, and its exemption during the first four taxable periods since incorporation — explanatory notes to the corporate income tax return of the Federal Public Service Finance (SPF Finances / FOD Financiën), tax year 2026 (exercice d'imposition / aanslagjaar).
Law of 15 July 2026 (Belgian Official Gazette, 29/07/2026), Articles 76, 80, b) and 88: the 20% limit on directors' benefits in kind (art. 2, § 1, 25° and art. 215, para. 3, 5° ITC 92), from tax year 2027; explanatory memorandum (Chamber, DOC 56 1243/001, p. 38-40): the benefit is included in total remuneration. Articles 36 and 198, § 1, 9° and 9°bis ITC 92: the benefit, valued by the accountant; the disallowed expense on the benefit of a car (FPS Finance, notes to the corporate income tax return, tax year 2026, p. 19).
Fiplan conventions, declared in the code (ventilation-paie.ts): the withholding tax paid over the following month.