
Staff: entering remuneration
For a salaried employee, you enter the gross monthly salary; Fiplan calculates the rest: contributions, payroll withholding tax (précompte professionnel / bedrijfsvoorheffing), net pay, double holiday pay (double pécule de vacances / dubbel vakantiegeld), and a companion line for the employer charges, created automatically.
What it is for
Remuneration costs more than its gross amount: the employer pays its social security contributions and, for a white-collar employee (employé / bediende), double holiday pay. Fiplan adds them from a single amount, so that the plan never underestimates staff costs.
Steps
- Open Encoding, then Remuneration, and click New.
- Choose the PCMN Account, the account in the Belgian minimum chart of accounts (PCMN / MAR): a
620…account for a salaried employee (for example620200, white-collar employees), a6181…account for the director. Give a Title (“Sales assistant”). - For a salaried employee, choose the Worker type: Employee (white-collar) or Worker (blue-collar, ouvrier / arbeider).
- Enter the Gross monthly salary and, if needed, the Annual bonus (as a % of the gross monthly salary) and the 13th month.
- Open Adjust rates to check the Withholding tax and the Employer NSSO (employer contributions to the National Social Security Office, ONSS / RSZ), both proposed by default.
- If the employee receives a benefit in kind (a car, housing…), open the Benefits in kind (valued at a flat rate) block, folded as long as no amount is entered: the benefit's annual amount, financial year by financial year, under Car or Other (housing, loan, options…). For a car, answer Does the company pay for the fuel?: saving waits for the answer.
- Check the Start period and the End period, read the breakdown on the right and click Save. Fiplan also creates the line “Employer charges – Sales assistant” (account 621000).
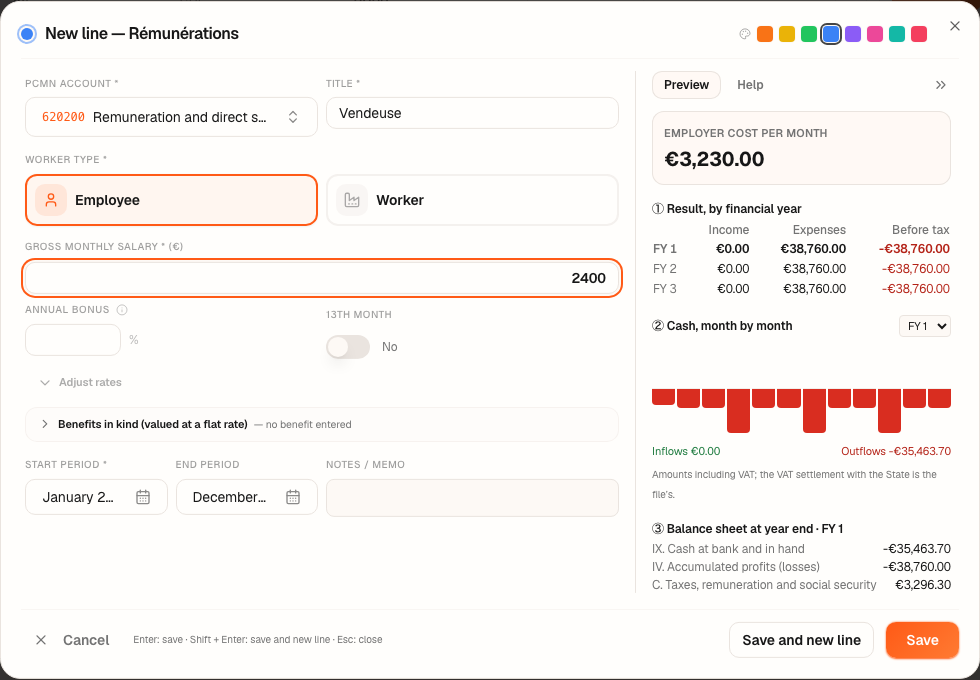
Worked example · Boulangerie Dupont SRL
A sales assistant, a white-collar employee, €2,400.00 gross per month, over the whole term of the plan, at the default rates.
| Each month | Rate | Amount |
|---|---|---|
| Gross salary | 2,400.00 | |
| Personal NSSO | 13.07% | 313.68 |
| Taxable base | 2,086.32 | |
| Withholding tax | 20% | 417.26 |
| Net estimate | 1,669.06 | |
| Employer NSSO | 25% | 600.00 |
| Monthly employer cost | 3,000.00 |
Over the year, a white-collar employee's double holiday pay (92% of the gross monthly salary, i.e. €2,208.00) is added, with its employer contributions:
The companion line 621000 carries what exceeds the twelve gross salaries: €38,760.00 − €28,800.00 = €9,960.00 per financial year.
Pitfalls
620… account opens the employee form, a 6181… account the director's form. On any other account 62, the screen shows no amount field: the line would be saved without figures.What it changes · 2027
Source
NSSO (ONSS / RSZ): the worker's personal contribution is 13.07% of gross pay; 25% is the employer rate proposed by default for a white-collar employee, to be adapted. NSSO administrative instructions 2026/3, on gross pay at 100% or at 108%: for manual workers and similar workers under the private-sector holiday scheme, social security contributions are calculated on gross pay increased by 8%.
Income Tax Code 1992 (CIR 92 / WIB 92): art. 36 (the benefit in kind, valued by the accountant); art. 198, § 1, 9° and 9°bis (the disallowed expense on the benefit of a car — FPS Finance, notes to the corporate income tax return, tax year 2026, p. 19); art. 219septies (the separate levy, not calculated).
Annual holiday legislation (Law of 28 June 1971): single holiday pay is the pay for the holidays; double holiday pay is a supplement.
Minimum standard chart of accounts (plan comptable minimum normalisé / minimumindeling van een algemeen rekeningenstelsel): accounts 620 (remuneration), 621 (employer social security contributions), 453 (taxes withheld), 454 (NSSO), 455 (remuneration payable).
Fiplan conventions, declared in the code (ventilation-paie.ts): NSSO contributions grouped by quarter and paid the following month, withholding tax paid the following month, net pay paid in the same month — modelling conventions, not legal dates.